 Skip to content
Small Personal Loans UK: A Complete Guide to Borrowing in 2026
- Michelle
- Finance
Did you know that by the end of 2025, total personal debt in the UK hit a staggering £1.94 trillion? It’s a heavy figure that reflects a reality many of us feel every day. When an unexpected car repair or a broken boiler disrupts your budget, the pressure is immediate. You’re likely worried that a less-than-perfect credit score will lock you out or that hidden fees will make a bad situation worse. It’s completely normal to feel anxious about how borrowing might impact your financial record.
We believe you deserve a transparent, supportive path to managing your finances. This guide shows you how to secure small personal loans uk without the stress, focusing on what you can afford now rather than mistakes from the past. You’ll learn how to decode the real cost of credit, understand new 2026 FCA regulations, and find a lender that treats you as a person. We’ll break down eligibility based on ONS economic data and show you how to get a rapid decision today.
Key Takeaways
- Learn how to choose the right borrowing amount when applying for small personal loans uk to secure immediate emergency liquidity without overstretching your budget.
- Master the difference between representative APRs and your actual total cost of credit whilst ensuring you are fully protected by FCA price caps.
- Discover the standard criteria needed for a rapid decision and how a soft search checks your eligibility with zero impact on your credit file.
- Find out how using a free, non-judgemental broker matches you with an extensive network of lenders who value your personal autonomy over a traditional credit score.
Understanding Small Personal Loans in the UK (2026)
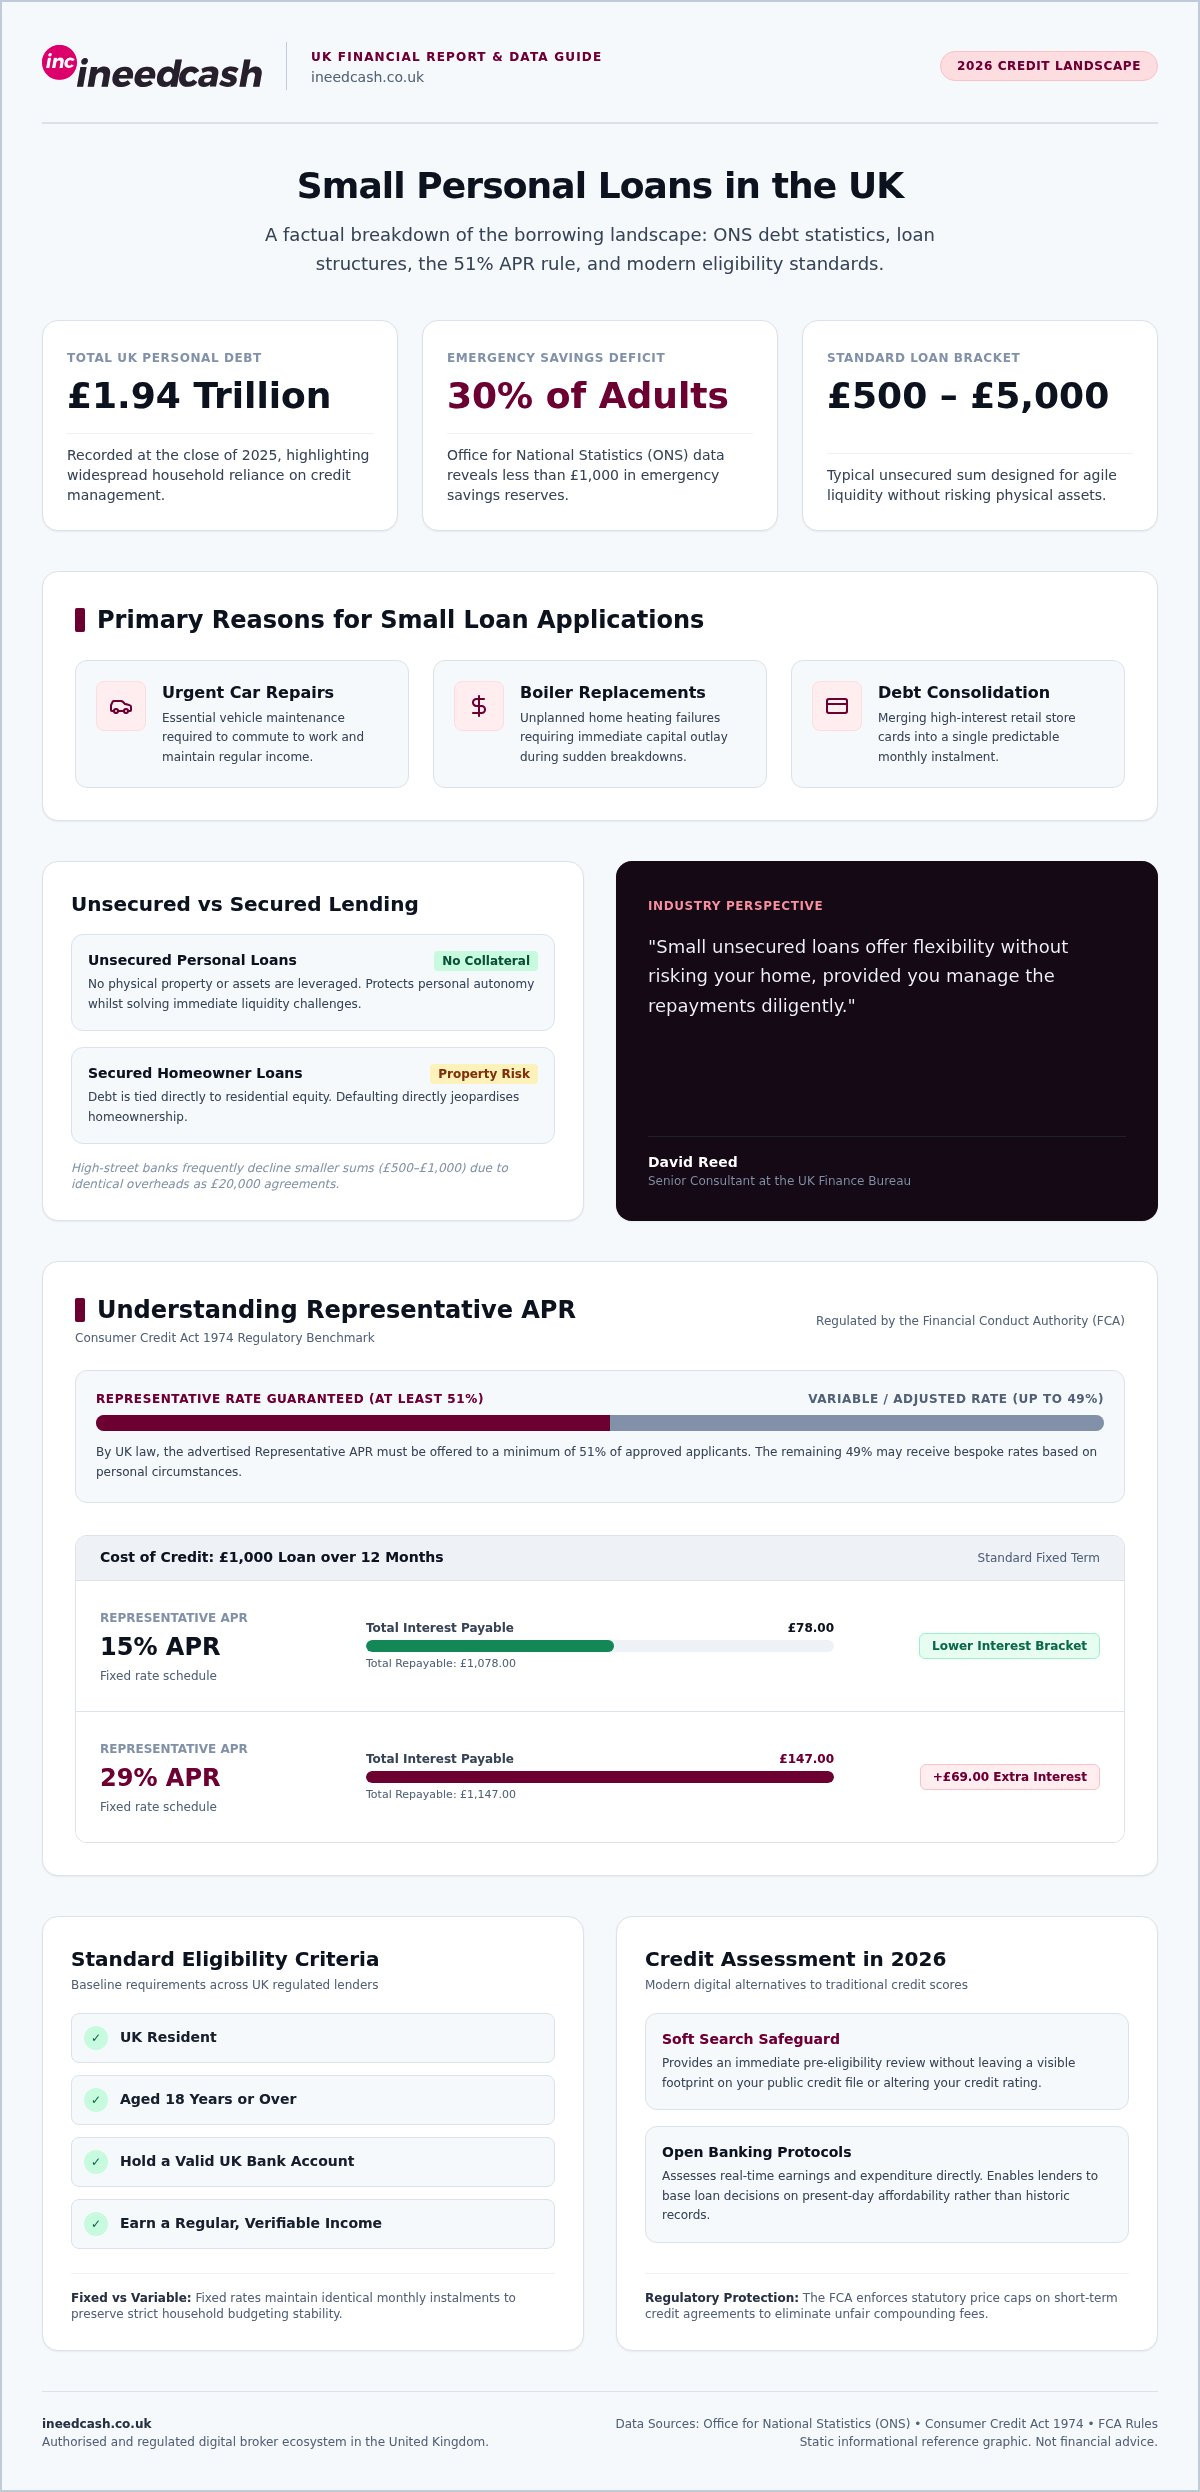
Small personal loans uk are unsecured borrowing options typically ranging from £500 to £5,000. In 2026, whilst inflation fluctuates, the demand for emergency liquidity remains high amongst households. According to recent data from the Office for National Statistics (ONS), approximately 30% of UK adults have less than £1,000 in emergency savings. This lack of a financial cushion makes access to agile credit essential for survival.
As noted in a recent Guardian finance feature on UK household resilience, these funds are primarily used for urgent car repairs, boiler replacements, or consolidating high-interest store cards.
Why Traditional Banks Often Say No
High-street banks often prioritise larger, long-term loans over smaller products. Processing a £500 loan requires the same administrative work as a £20,000 agreement, making small loans less profitable for traditional institutions. This has led to a significant shift towards digital-first brokers. These facilitators cater to the underserved demographic that needs rapid, flexible solutions without the rigid gatekeeping of a traditional bank branch.
Unsecured vs Secured: Know the Difference
It is vital to understand that unsecured loans require no collateral, meaning your assets are not at immediate risk. In contrast, homeowner loans are secured against your property. “Small unsecured loans offer flexibility without risking your home, provided you manage the repayments diligently,” explains David Reed, a senior consultant at the UK Finance Bureau. Choosing an unsecured option protects your personal autonomy whilst providing the necessary funds to handle life’s unexpected expenses.
The Real Cost of Credit: Comparing APRs and Fees
Understanding the actual cost of borrowing saves you money. When searching for small personal loans uk, you will always see a Representative APR. By law, under the Consumer Credit Act 1974, this rate must be offered to at least 51% of successful applicants. The remaining 49% might receive a higher rate based on their individual situation. Rest assured that the Financial Conduct Authority (FCA) enforces strict price caps on short-term credit, protecting you from unfair charges. However, you must still check for hidden fees like late payment charges or early repayment penalties that can quietly increase your debt.
To see how interest rates change your total debt, look at this simple comparison for a £1,000 loan repaid over 12 months:
| Loan Amount | Repayment Term | Representative APR | Total Interest Payable |
|---|---|---|---|
| £1,000 | 12 Months | 15% | £78.00 |
| £1,000 | 12 Months | 29% | £147.00 |
Fixed vs Variable Interest Rates
Most small personal loans in the UK feature fixed interest rates. This means your monthly instalment stays exactly the same, making budgeting straightforward during unpredictable times. Always check the “Total Amount Repayable” figure before signing. This number tells you the exact cost of the credit, helping you avoid surprises.
The Broker Advantage: Finding the Best Fit
We work hard to simplify this process. As an FCA-regulated broker, I Need Cash scans an extensive panel of independent lenders on your behalf. You can complete our cash loan applications safely online to review competitive rates without facing rigid upfront judgments.
Eligibility and the Modern Application Process
Applying for small personal loans uk is fast and straightforward. To qualify, you must be a UK resident aged 18 or over, hold a valid bank account, and earn a regular income. Most modern providers now utilise a “Soft Search” system to check your eligibility. This is a vital safety net. It allows you to view your chances of approval instantly without impacting your credit score or leaving a visible mark on your financial record.
The Power of Open Banking
Lenders in 2026 look beyond historical mistakes by using Open Banking technology. This system securely reviews your real-time income and spending patterns to assess current affordability. A recent report by Financial News UK highlights how this shift has boosted approval rates for responsible borrowers. For a deeper look at this technology, read our guide on Open Banking Loans.
Applying with Bad Credit: What You Need to Know
A low credit score is no longer an automatic barrier. Specialised lenders focus on your capacity to manage money today. Actionable tip: Organise your recent bank statements to show consistent income and steady bill payments before applying. “Demonstrating stable day-to-day cash management is far more valuable than a past default,” states personal finance expert Alistair Vance from the UK Consumer Panel.
Step-by-Step to Your Loan Decision
- Step 1: Determine your exact borrowing needs.
- Step 2: Use a broker to check eligibility risk-free.
- Step 3: Review your personalised quote.
An Affordability Assessment acts as the primary tool lenders use to protect your financial health. Ready to see your options? Check your eligibility today for a fast, supportive decision.
Responsible Borrowing: Finding Your Financial Ally
Managing your money is about maintaining personal autonomy. We act as a non-judgemental facilitator, matching you with lenders who value your current stability rather than historical data. It’s crucial to borrow only what you truly need, ensuring the monthly repayments fit comfortably within your existing budget. This disciplined approach prevents financial strain and keeps your future goals on track.
The Stress-Free Broker Process
Using a broker provides a streamlined experience. You complete just one application, and we scan an extensive network of independent UK lenders on your behalf. This saves time and reduces the stress of individual submissions. If you feel overwhelmed by debt, we strongly recommend seeking free, impartial advice from Gov.uk MoneyHelper before taking out new small personal loans uk.
Why Choose I Need Cash?
“A regulated broker acts as a vital buffer, ensuring consumers aren’t exposed to predatory lending practices,” notes James Sinclair, a lead researcher for the UK Debt Advocacy Group. We are authorised and regulated by the Financial Conduct Authority (FCA). Our matching service is free for all applicants. If your needs grow, we also offer homeowner loans for larger amounts.
Next Steps: Get Started Today
Move from financial anxiety to a clear, actionable solution today. You deserve a supportive partner that works on your behalf to find the most transparent credit options available. Don’t wait for the pressure to build. You can review your personalised options in minutes without any obligation. Ready to see your options? Get started here.
Empower Your Financial Future Now
You now have the tools to navigate the 2026 lending market with total confidence. By understanding the shift towards real-time affordability and the safety net of soft search technology, you can explore your options without fear. Remember that small personal loans uk should always be a tactical choice, supported by clear representative APRs and strict FCA protections. You don’t have to face financial hurdles alone or feel judged by outdated credit records anymore.
As an FCA Regulated Broker, we provide a no-obligation soft search that respects your financial history whilst prioritising your current needs. Our platform gives you immediate access to a wide panel of UK lenders, ensuring you find a solution that fits your unique budget. It’s time to move from uncertainty to empowerment. You deserve a facilitator that works on your behalf to secure a stable outcome. Apply for a small personal loan today and take control. We’re ready to assist you now.
Frequently Asked Questions
Can I get a small personal loan with very bad credit in the UK?
Yes, you can secure a loan even if your credit history isn’t perfect. Specialist lenders in our network focus on your current affordability rather than past mistakes. They use Open Banking to review your real-time income and expenditure. Whilst a very low score might limit mainstream options, we help you find providers who offer small personal loans uk tailored to your specific financial circumstances.
How long does it take for a small loan to be paid into my bank account?
Speed is a priority when you face an emergency. Most lenders in our panel aim for rapid decisions, often providing an answer within minutes of your application. Once you’re approved and have signed the agreement, funds are typically transferred via Faster Payments. This means the money could reach your bank account on the same day, or even within a few hours, depending on your bank’s processing times.
Will applying for a small loan affect my credit score?
Checking your eligibility through our service won’t impact your credit score at all. We use a soft search to match you with potential lenders, which remains invisible to other financial institutions. You only face a hard search if you decide to proceed with a specific loan offer and submit a final application. This transparent process allows you to shop around safely without damaging your future borrowing potential.
What is the difference between a payday loan and a small personal loan?
The main differences are the repayment term and the total cost. Payday loans are designed to be repaid in full on your next payday, often carrying very high interest rates. In contrast, small personal loans uk allow you to spread the cost over several months or years. This makes monthly instalments much more manageable and significantly reduces the daily interest rate, providing a more stable way to handle unexpected costs.
Are there any fees for using a broker like I Need Cash?
No, our service is completely free for all applicants. We act as a facilitator, matching you with a wide panel of regulated UK lenders without charging you any upfront or hidden fees. We receive a commission from the lender if your application is successful, so you don’t have to worry about extra costs. This ensures you get transparent assistance and access to competitive rates without any financial obligation to us.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.