 Skip to content
Reporting an Unauthorised Loan Company in the UK: What Happens Next
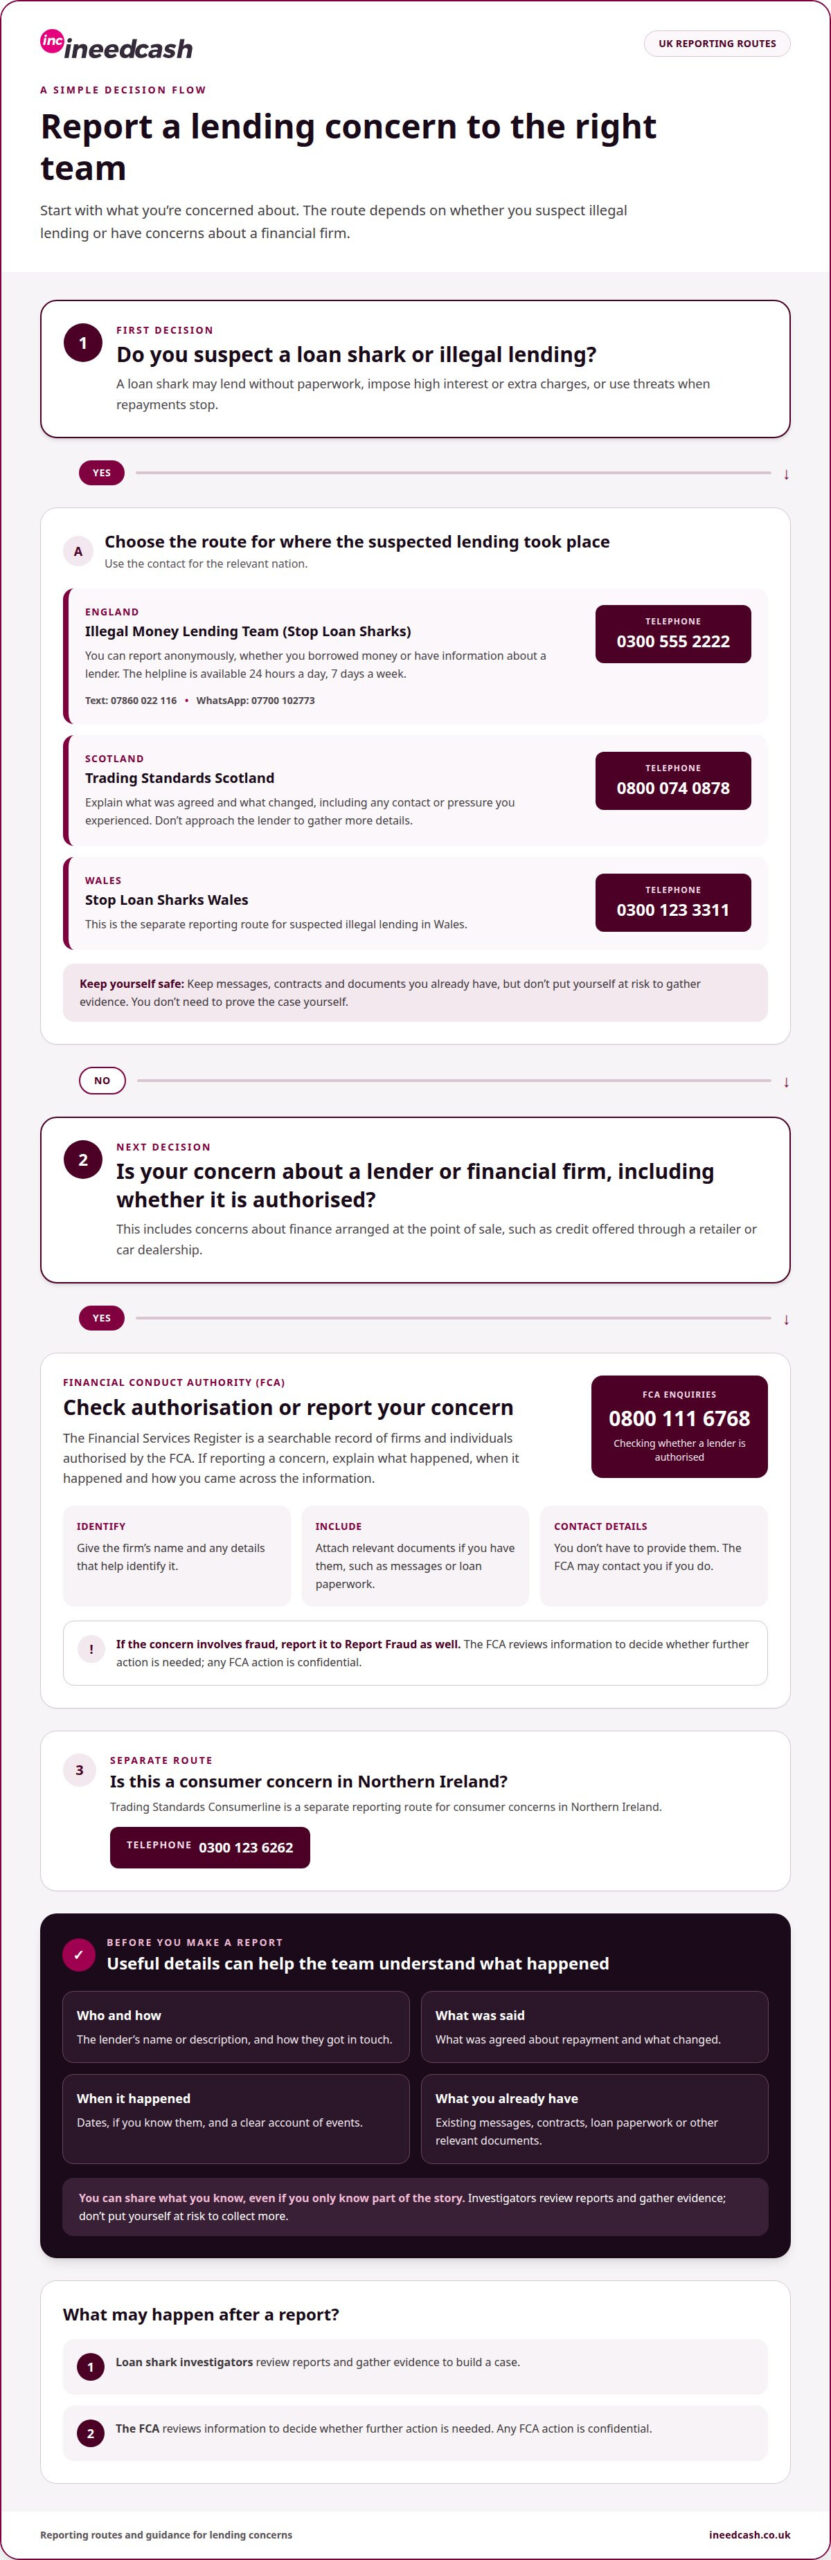
A report can put suspected illegal lending in front of the right team. In England, contact the Illegal Money Lending Team; in Scotland, report a loan shark to Trading Standards Scotland on 0800 074 0878.
If you’re unsure where to start, that’s understandable. Reporting an unauthorised loan company in the UK depends on whether you suspect a loan shark or have concerns about a firm providing regulated financial services. You can share what you know even if you’re worried about what might happen next.
This guide explains who to contact in England and Scotland, how the FCA fits in, and what may follow a report. Loan shark investigators review reports and gather evidence, while the FCA reviews information to decide whether further action is needed. The FCA keeps any action confidential. You’ll also learn what details can make a report useful and when a regulated loan may be a more suitable borrowing option.
Key Takeaways
- Report suspected loan sharks to the relevant team for your part of the UK, so your information reaches the right investigators.
- For questions about whether a lender is authorised, contact the Financial Conduct Authority on 0800 111 6768, according to the Financial Conduct Authority.
- You can share details and supporting documents with the FCA; its review may inform further action, though any action is confidential.
- Learn how to distinguish suspected illegal lending from concerns about a regulated lender, and what to expect after making a report.
Reporting wrongdoing by firms or individuals in regulated financial services
If you suspect wrongdoing by a lender or another financial firm, report it to the Financial Conduct Authority (FCA). When reporting an unauthorised lender to the FCA, explain what happened and provide any supporting details or documents you have.
Financial Conduct Authority register enquiries
The Financial Services Register is a searchable record of firms and individuals authorised by the FCA. Use it to look up a lender before deciding whether your concern relates to authorisation. In the UK, the Financial Conduct Authority can be contacted on 0800 111 6768 for enquiries about checking whether a lender is authorised. Give the firm’s name and any details that help identify it.
Reporting an unauthorised lender to the FCA
A report gives the FCA information to review when considering concerns about regulated financial services. Explain what the lender or individual did, when it happened, and how you came across the information. You can attach relevant documents, such as messages or loan paperwork. You don’t have to provide your contact details, but the FCA may contact you if you do. If your concern involves fraud, report it to Report Fraud as well.
In Northern Ireland, Trading Standards Consumerline can be contacted by telephone on 0300 123 6262. This is a separate reporting route for consumer concerns in Northern Ireland.
Finance arranged at the point of sale is also covered by lending rules. This includes credit offered through a retailer or car dealership, so report concerns about the lender or the way the finance was sold.
For business borrowing, an authorised lender must be registered with the FCA to lend less than £25,000 for business purposes. Individuals seeking personal credit can use authorised lending as an alternative to an unregulated lender. If considering borrowing secured against your home, read the homeowner loan information carefully and consider the repayment commitment.
What is the England Illegal Money Lending Team (IMLT)?
The England Illegal Money Lending Team investigates suspected illegal lending and supports people affected by loan sharks. In England, call 0300 555 2222; the Stop Loan Sharks helpline is available 24 hours a day, 7 days a week. You can report anonymously, whether you borrowed money or have information about a lender.
Recognising illegal lending
A loan shark is an illegal moneylender who may lend without paperwork, impose high interest or extra charges, and use threats when repayments stop. Keep messages, contracts and documents you already have, but don’t put yourself at risk to gather evidence. Investigators review reports and gather evidence to build a case.
Responsible lending and complaints
The Consumer Credit Act 1974 is relevant to regulated credit complaints. The OFT’s Irresponsible Lending Guidance says lenders should assess whether borrowers can “repay lending sustainably”, considering the effect of payments on borrowers, not only the likelihood of repayment to the lender. This is an attributed summary of the guidance’s principle, not a promise about the outcome of an individual complaint.
If a regulated loan feels unaffordable, explain the difficulty to the lender and show how repayments affect your finances. The Financial Ombudsman considers whether the lender met its obligations and whether a failure caused you loss. A complaint about unaffordable regulated credit is different from reporting suspected illegal lending to investigators.
Limits on business-loan investigations
The IMLT can investigate certain business-purpose loans under £25,000 when the borrower is a sole trader, a partnership with fewer than four partners, or an unincorporated association. It cannot investigate loans made to limited companies. The borrower’s legal structure and the loan’s purpose therefore matter when deciding whether the team can investigate.
If you’ve borrowed from a suspected illegal lender, share what you know with investigators. Don’t assume that a demand for repayment or interest settles what you legally owe; the facts of the agreement matter.
Scotland loan shark reporting contacts
A loan shark reporting contact is the service to approach with information about suspected illegal lending. Use the contact for the nation where the lending took place, and share only details you know are accurate.
Report a loan shark in Scotland
In Scotland, contact Trading Standards Scotland on 0800 074 0878 to report a loan shark. For example, if someone lends money privately and then demands unexpected repayments, explain what was agreed and what changed. Describe any contact or pressure you experienced. Don’t approach the lender to gather more details.
Contacts in England and Wales
In England, contact the Illegal Money Lending Team, also known as Stop Loan Sharks. You can report by text on 07860 022 116 or WhatsApp on 07700 102773. The telephone number is given in the previous section. In Wales, contact Stop Loan Sharks Wales on 0300 123 3311. These are separate national routes, so use the service relevant to where the suspected lending occurred.
Reporting anonymously
An anonymous report lets you share information without giving your contact details. In England, you can report anonymously whether you borrowed from the lender or witnessed their activity. Give a clear account of what happened, even if you know only part of the story. Investigators can assess the information you provide; you don’t need to prove the case yourself.
Details that can help
Before contacting a service, note the lender’s name or description, how they got in touch, and what they said about repayment. Include dates or existing messages if you have them. These practical details make a report more useful without requiring you to investigate. For reports in Scotland, contact Trading Standards Scotland; Stop Loan Sharks handles reports in England, and Wales has its own team.
Confidentiality and follow-up
Confidentiality means the FCA reviews information without disclosing what action it takes. It assesses reports to decide whether its teams need to take further action. You may not learn whether a firm or individual is being investigated, even after submitting detailed information. The lack of an update does not mean your report was ignored.
Follow-up means any contact the FCA makes with someone who has shared their details. It may contact you to discuss your report, so include accurate contact information if you want that possibility. You don’t have to provide your details when reporting. If you choose not to, the FCA can still receive your information but cannot contact you directly about it.
To make your report useful, give a clear account of what happened and identify the firm or individual involved. Include dates, how the lender contacted you, and what was said about the credit or repayment. Attach messages, agreements or account statements if they help explain events. Only send information you can share lawfully; reporting does not remove statutory legal requirements.
The FCA may use information to build a picture of conduct risks or inform policy development, even if it doesn’t lead to formal action against a firm. Your report can therefore help the FCA understand patterns across financial services. Keep a record of what you submitted, when you sent it, and any documents you included. If you borrowed money, preserve relevant statements and messages so you can explain the history clearly if asked.
Reporting and applying for credit are separate decisions. If you’re considering borrowing through a regulated route after making a report, start an application only when the repayments fit your circumstances.
I Need Cash
I Need Cash is a credit broker that helps people explore borrowing options through a network of independent lenders. If you’ve reported suspected illegal lending but still need to consider borrowing, its options include Personal Loans, Short Term Loans, Homeowner Loans and Bad Credit Loans. Applying for a loan is separate from making a report, and won’t investigate a lender or resolve a complaint. Consider whether repayments fit your circumstances before applying.
To discuss your borrowing needs, get started with I Need Cash.
Choose your next step with confidence
Give yourself space to decide what you need next. Reporting an unauthorised loan company in the UK is one step; planning your finances is another. You don’t have to rush into a new commitment because a previous borrowing experience has left you under pressure. Take time to consider your priorities and what you can manage comfortably.
If borrowing is still part of your plans, consider the full repayment commitment alongside your regular bills and existing credit. Think about whether the loan would address a genuine need and whether the payments would remain manageable if your circumstances changed. A clear budget can help you make that decision on your own terms.
For help exploring your borrowing options, contact I Need Cash. Move forward at a pace that feels right, with your needs and financial wellbeing at the centre.
For questions about whether a lender is authorised, the Financial Conduct Authority (FCA) can be contacted on 0800 111 6768, according to the FCA.
Frequently Asked Questions
What happens after you get in touch?
The relevant team reviews the information and decides what to do next. The FCA may contact you if you provide your details, but it keeps any action confidential and won’t disclose what it decides to do. Your information may still help build a picture of conduct risks or inform policy, even if it doesn’t lead to formal action against a firm.
How do I report an unauthorised loan company in the UK?
Choose the reporting route for the type of concern and where the lending took place. Contact the Illegal Money Lending Team in England, Trading Standards Scotland in Scotland, or Stop Loan Sharks Wales in Wales. In Northern Ireland, telephone Trading Standards Consumerline on 0300 123 6262, according to Trading Standards Consumerline. For concerns about regulated financial services, report the matter to the FCA.
How can I check whether a UK lender is authorised by the FCA?
Search the Financial Services Register for the lender’s name and check whether it appears as an authorised firm. If you’re uncertain whether a lender is authorised, contact the Financial Conduct Authority on 0800 111 6768. Keep the lender’s name and any correspondence to hand so you can describe the firm you’re asking about clearly.
What is the FCA Firm Checker and Financial Services Register?
The Financial Services Register is a searchable record of firms and individuals authorised by the FCA. The Firm Checker helps you look for information about a financial firm; use the register to search for its listing. If you’re unsure how to interpret a result, contact the FCA for help with an authorisation enquiry rather than relying on a lender’s claims alone.
What evidence should I collect before reporting an unauthorised loan company?
Share what you already have; you don’t need to investigate or gather proof yourself. Useful material may include loan paperwork, messages, emails, payment records, or a note of what the lender said and when. Give the firm’s name or description and explain how you encountered it. The FCA accepts report details and attachments to help review concerns.
What should I do if I have already borrowed money from an unauthorised lender?
Report the lender and explain what you borrowed, what repayments were requested, and whether you received paperwork or threats. Keep existing messages and payment records, and don’t confront the lender to obtain more evidence. A loan shark is different from an authorised lender, so don’t assume the agreement or any demand is legally settled simply because money changed hands.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.