 Skip to content
Personal Loan Broker UK: How to Choose the Right Broker
- Michelle
- Finance
Could applying through more lenders make it harder to choose the right loan? Searching “personal loan broker uk” is often the first step when rates, eligibility checks and credit-file questions feel confusing. A broker can connect you with lenders on its panel, but not every lender will consider every applicant, and a referral doesn’t mean you’ll be approved.
Before you proceed, check which lenders the broker works with, whether it appears on the Financial Conduct Authority’s Register, what information it needs and whether any fees apply. Ask whether a lender may carry out a soft or hard credit search. If you receive an offer, compare its repayments and total cost with your budget and other options. This guide explains what a UK personal loan broker does, what to check before sharing your details and how to assess an offer without rushing into borrowing.
Key Takeaways
- A personal loan broker uk introduces applicants to lenders. The lender decides whether to offer credit.
- Before sharing details, check the broker’s FCA Register entry, lender panel and how it uses your information.
- Compare APR, total repayable, term, instalments and any disclosed fees. Check that repayments fit your budget.
- A referral isn’t an offer or approval. Read the terms carefully before deciding whether to borrow.
What does a personal loan broker in the UK actually do?
A personal loan broker introduces applicants to lenders. The lender, not the broker, assesses the application and decides whether to offer credit and on what terms. A broker may collect the details you provide and use them to identify potential options from its lender panel. That panel won’t include every lender, and a potential match doesn’t mean the lender or product will suit you.
In short, a broker can connect you with a lender, but only the lender makes the credit decision. For a general overview of what a credit broker is, see this background reference. The FCA’s Principle 12 states: “A firm must act to deliver good outcomes for retail customers.” This is wording from the Financial Conduct Authority’s Principles for Businesses, including its Consumer Duty. I Need Cash describes itself as a credit broker, not a lender. Check its current disclosures and entry on the FCA Register before sharing information.
Broker, lender and loan agreement: who does what?
The broker collects the application details you provide and may present potential lender matches. The lender assesses your eligibility and affordability, considers your application and decides whether to make an offer. If you receive one, identify the lender and read its agreement carefully. Check the repayments, interest rate, term and any relevant charges, then consider whether the payments fit your budget.
A personal loan broker uk search can help you explore options, but a referral isn’t an offer, approval or obligation to borrow. If you’re considering borrowing secured against your home instead, read the separate homeowner loan information and understand how that option differs before proceeding.
What does free to applicants mean?
I Need Cash describes its service as free to applicants. Check the current terms and ask directly whether you would pay a fee. You can also ask whether the broker receives commission or other payment from a lender, and how that relates to the options presented to you. Don’t assume how a broker is paid. Look for a clear explanation so you can understand the service before deciding whether to continue.
How to assess a personal loan broker before applying
When choosing a personal loan broker uk, look beyond headline claims. Check that the firm explains who it is, which lenders it works with and what happens to your information. Use this checklist before submitting an application:
- Regulatory details: Find the firm’s current FCA Register entry and check its status and permissions.
- Lender panel: Ask which lenders may consider your application and whether the panel has any limits.
- Data use: Read the privacy information to see how your details may be used, shared and retained.
- Credit searches: Ask when a search may happen and whether it could be a hard search.
An application may ask for details such as your income, regular outgoings and address. Provide accurate information, and check how it will be handled before submitting it. You can review the information requested through the cash loan application page before deciding whether to proceed.
Which questions should you ask a personal loan broker?
Ask whether your circumstances fall within the broker’s lender panel and whether every lender considers every application. Find out what happens to your details if the broker can’t identify a potential match. Ask when a credit search may take place and whether it could be a hard search. If any part of the process is unclear, request an explanation before continuing.
What should you check on the FCA Register?
Search for the broker’s firm name on the FCA Register. Compare its listed status, relevant permissions and contact details with the information on the broker’s own site. If anything doesn’t match, pause and ask the firm to clarify.
The FCA Register can help you check a firm’s status and permissions, but it can’t guarantee loan approval or tell you whether a particular loan suits your budget. After checking the basics, review the broker’s get started information and decide whether to take the next step.
Compare personal loan options without overlooking affordability
A low monthly repayment can look appealing, but it doesn’t show the full cost. If you use a personal loan broker uk service to explore options, compare each lender’s offer with your budget and read the agreement before deciding.
Which loan details matter beyond the monthly repayment?
Compare the rate you’re offered with any representative APR shown in advertising. Then check the total repayable, repayment term and any fees or conditions. A longer term may reduce each instalment, but it can change the total cost of borrowing.
For context, Which? reported representative APRs of around 6.1% to 6.4% for a £10,000 personal loan over five years on 1 September 2026. This is an advertised representative range, not a promise of the rate an individual applicant will receive. Check the lender’s actual offer.
| Detail | What to check |
|---|---|
| APR | Compare the advertised representative APR with the rate offered to you. |
| Total repayable | Check the full amount due over the agreement. |
| Term and instalments | Note the repayment period and the amount of each payment. |
| Fees and conditions | Review any disclosed charges and key agreement terms. |
Set the proposed instalment alongside essential bills and existing credit commitments. The FCA’s official regulatory guide explains standards for credit brokers. When comparing offers, focus on the lender’s actual terms and your circumstances. A homeowner loan is a separate option with different considerations. Read the homeowner loan information before weighing it against an unsecured personal loan.
Could a broker search affect your credit file?
That depends on the lender and the stage of your application. Before proceeding, ask whether a credit check will happen and whether it will be a soft or hard search. Don’t assume a broker enquiry will leave your credit file unaffected.
To review the process and potential options, see I Need Cash’s get started information. Read the details carefully before deciding whether to continue.
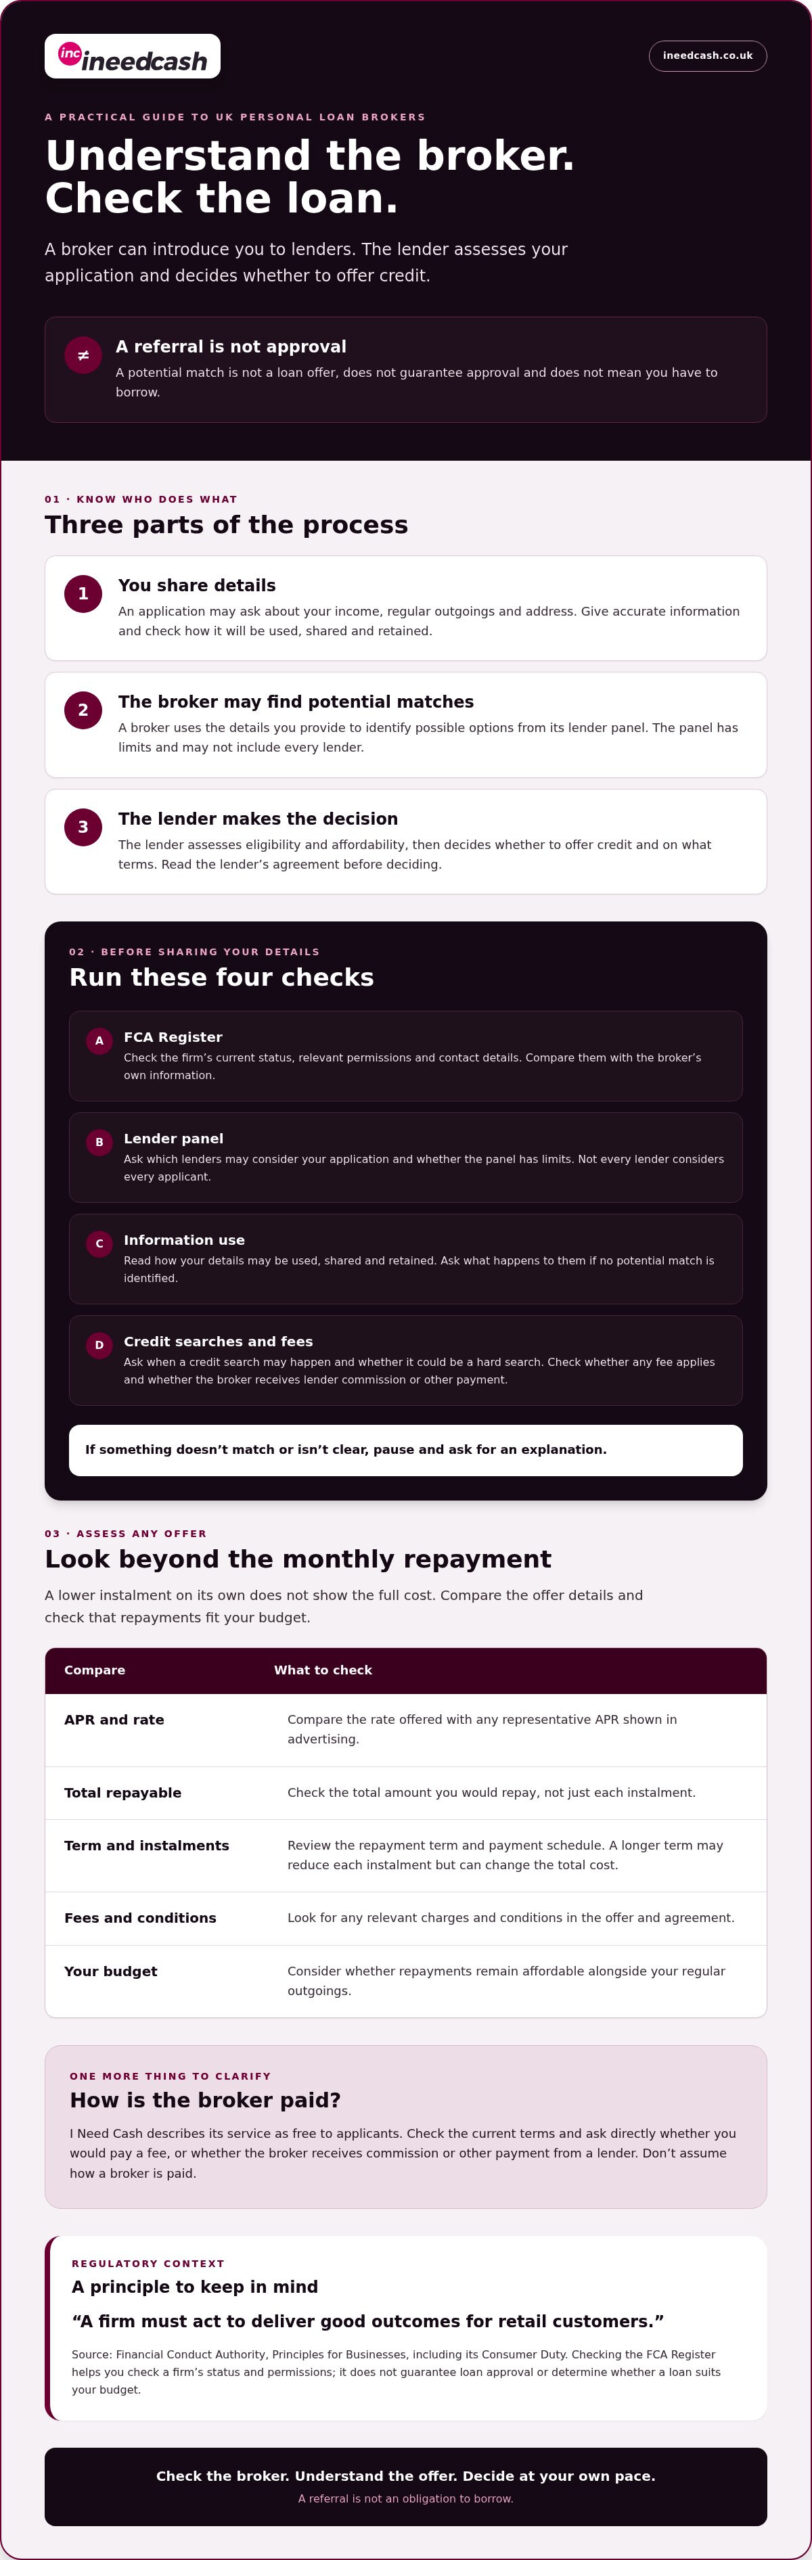
What happens after you contact a UK personal loan broker?
Contacting a personal loan broker uk is a way to explore potential options, not a commitment to borrow. Take time to check the details and decide whether an option works for you.
- Share accurate details. Provide complete information about your circumstances and borrowing request.
- Review potential options. The broker may refer your details to lenders on its panel. A referral or match isn’t an offer or approval.
- Check the lender’s terms. Review the rate, repayments, term, total repayable and any disclosed fees.
- Make your decision. Proceed only if the final offer meets your needs and fits your budget.
To understand what the next step involves, you can review the get started information from I Need Cash. This doesn’t guarantee a lender match or loan approval, and you’re not obliged to accept an offer.
What information might an application ask for?
A form may ask for details to confirm your identity, income, regular outgoings and the amount you want to borrow. Check each answer before submitting it and use a secure application channel. The cash loan application page shows where to explore the application process, but completing a form doesn’t guarantee eligibility.
When should you decide not to proceed?
Pause if you don’t clearly understand the repayment amount, loan term or total cost, or if the instalments could leave too little for essential bills and existing commitments. Compare the lender’s final offer with the amount you need and your household budget. If your circumstances have changed, reassess whether borrowing is still manageable. You don’t have to accept an offer simply because a broker referred you to a lender.
If you want to consider the process, review the options and information before deciding whether to continue.
Choose your next borrowing step with confidence
A personal loan broker uk can introduce you to potential lenders, but the lender decides whether to offer credit. Before applying, check the broker’s current details on the FCA Register, ask how your information may be used and find out what type of credit search could take place.
Look beyond the monthly instalment when comparing an offer. Check the rate, term, total repayable and any disclosed fees, then consider whether the repayments fit your household budget. A referral isn’t approval, and you can take time to decide whether borrowing is right for you.
I Need Cash describes itself as a credit broker, not a lender, and says its service is free to applicants. Check the current terms and FCA Register details before proceeding. Explore potential options with I Need Cash and take the next step only when you’ve reviewed the information and decided how you want to proceed.
Frequently Asked Questions
What is a personal loan broker in the UK?
A personal loan broker introduces applicants to lenders that may consider their borrowing request. A personal loan broker uk may collect your details and look for potential matches across its lender panel, but that panel won’t include every lender and a match doesn’t mean you’ll be approved. The lender assesses your application and decides whether to offer credit, including the rate and terms.
Is a personal loan broker the same as a lender?
No. A broker acts as an intermediary, while a lender provides the credit and decides what to do with your application. I Need Cash describes itself as a credit broker, not a direct lender, and connects applicants with independent lenders. If you receive a referral, check which lender is making the offer and read its agreement before deciding whether to accept.
Can a personal loan broker guarantee approval?
No. A broker can’t guarantee that a lender will approve your application or offer particular terms. The lender assesses your details and makes a decision using its own criteria. Treat the broker’s service as a way to explore potential options, not a promise of credit. Before proceeding, compare the repayments and total amount repayable with your budget.
Does using a loan broker affect your credit score?
It depends on what checks are made and when. A broker or lender may carry out a soft or hard credit search at different stages. A hard search can appear on your credit file and may affect your score. Ask which type of check will take place before submitting an application or authorising a search. Don’t assume an enquiry has no effect.
Do personal loan brokers charge applicants a fee?
Fees vary by broker, so ask before sharing details or applying. I Need Cash describes its service as free to applicants, but check the current terms and ask whether a fee applies to you. You can also ask whether the broker may receive commission or other payment from a lender and how this is explained. Read the relevant disclosures before deciding whether to continue.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.