 Skip to content
Top Lenders for Car Loans in the UK: Find the Best Rates
- Michelle
- Finance
The lowest advertised APR isn’t always the rate you’ll be offered. Rates from lenders for car loans can vary with your circumstances, so compare personalised offers rather than relying on a headline figure. If you’re choosing between a personal loan and dealer finance, the agreements can differ in cost, ownership and what happens at the end of the term.
Compare the total amount repayable as well as the monthly payment, and check whether the repayments fit your budget. The Bank of England’s UK interest-rate data provides wider context, but it can’t tell you what rate a lender will offer. This guide explains the main borrowing routes and what to weigh up before applying.
You’ll also learn what lenders may consider when assessing affordability and how a broker can help you explore options. The FCA’s Consumer Duty guidance offers useful context on firms’ responsibilities to consumers.
Key Takeaways
- Understand what a car loan covers and why “lender” can refer to different types of finance providers.
- See how lenders assess applications, including the role credit history may play, without assuming any one factor decides the outcome.
- Compare lenders for car loans on a like-for-like basis, considering APR, repayments, total cost, term and any stated fees.
- Learn how I Need Cash connects applicants with FCA-regulated lenders and what to expect from a free, no-obligation quote.
Lenders for car loans: understand your borrowing options before you apply
A car loan is money borrowed to help pay for a vehicle, with repayments made over a term agreed with the lender. “Lender” can mean a bank, a vehicle finance provider or a lender introduced through a credit broker. The lender provides the funds and sets the offer’s rate, repayments and conditions after assessing your application.
A credit broker introduces applicants to potential lenders; the lender, not the broker, decides whether to offer finance and provides the funds. Knowing the difference helps you understand who is arranging your options and who is responsible for the loan agreement. For a general overview of car finance options in the UK, you can also explore how different arrangements are structured.
Personal car loan or dealer-arranged finance?
With a personal loan, you borrow separately to pay for the car. Dealer-arranged finance is organised as part of the purchase and may link ownership to the agreement’s terms. Neither route is automatically better. Compare the total repayable, monthly payments, when you own the car and what happens at the end of the agreement. I Need Cash helps applicants explore car borrowing options, including car finance borrowing options.
Why the lender behind an offer matters
Different lenders can assess the same application differently. Eligibility, rates and terms depend on the lender’s criteria and your circumstances. An advertised rate or representative APR is an example, not a promise that you’ll receive that rate. Check who is providing the funds and read the personalised terms before focusing on the headline figure. That makes it easier to compare lenders for car loans based on what you may actually repay.
How car-loan lenders assess your application and set an offer
No single detail guarantees that a lender will accept an application. Lenders consider affordability alongside the information you provide, and each makes its own decision. Your credit history may help a lender understand how you’ve managed borrowing, but it does not decide the outcome on its own.
What information may matter to a lender?
Provide accurate, up-to-date details about your income, regular commitments and the amount you want to borrow. Lenders use the information to assess whether repayments could fit your budget. They may weigh it differently and apply their own criteria, so one lender’s decision doesn’t predict another’s. FCA-regulated firms are expected to act to deliver good outcomes for customers under the FCA’s Consumer Duty.
Before requesting a quote, check your figures and consider what repayment you could manage alongside existing bills. Be open about your circumstances. A clear, complete application helps lenders assess the information provided, but cannot guarantee acceptance or a particular rate.
What happens during an initial credit search?
An initial soft search for an I Need Cash quote doesn’t affect your credit score. It is used at the quote stage to explore potential options. A soft search is different from a full credit check, and it doesn’t mean no further checks will take place.
A lender may carry out a full credit check later, depending on the loan type and your application. Read the lender’s information so you understand what checks may follow before deciding whether to proceed. To explore options, start an online quote with I Need Cash, a credit broker that connects applicants with FCA-regulated lenders.
Compare car-loan lenders by total repayment, term and affordability
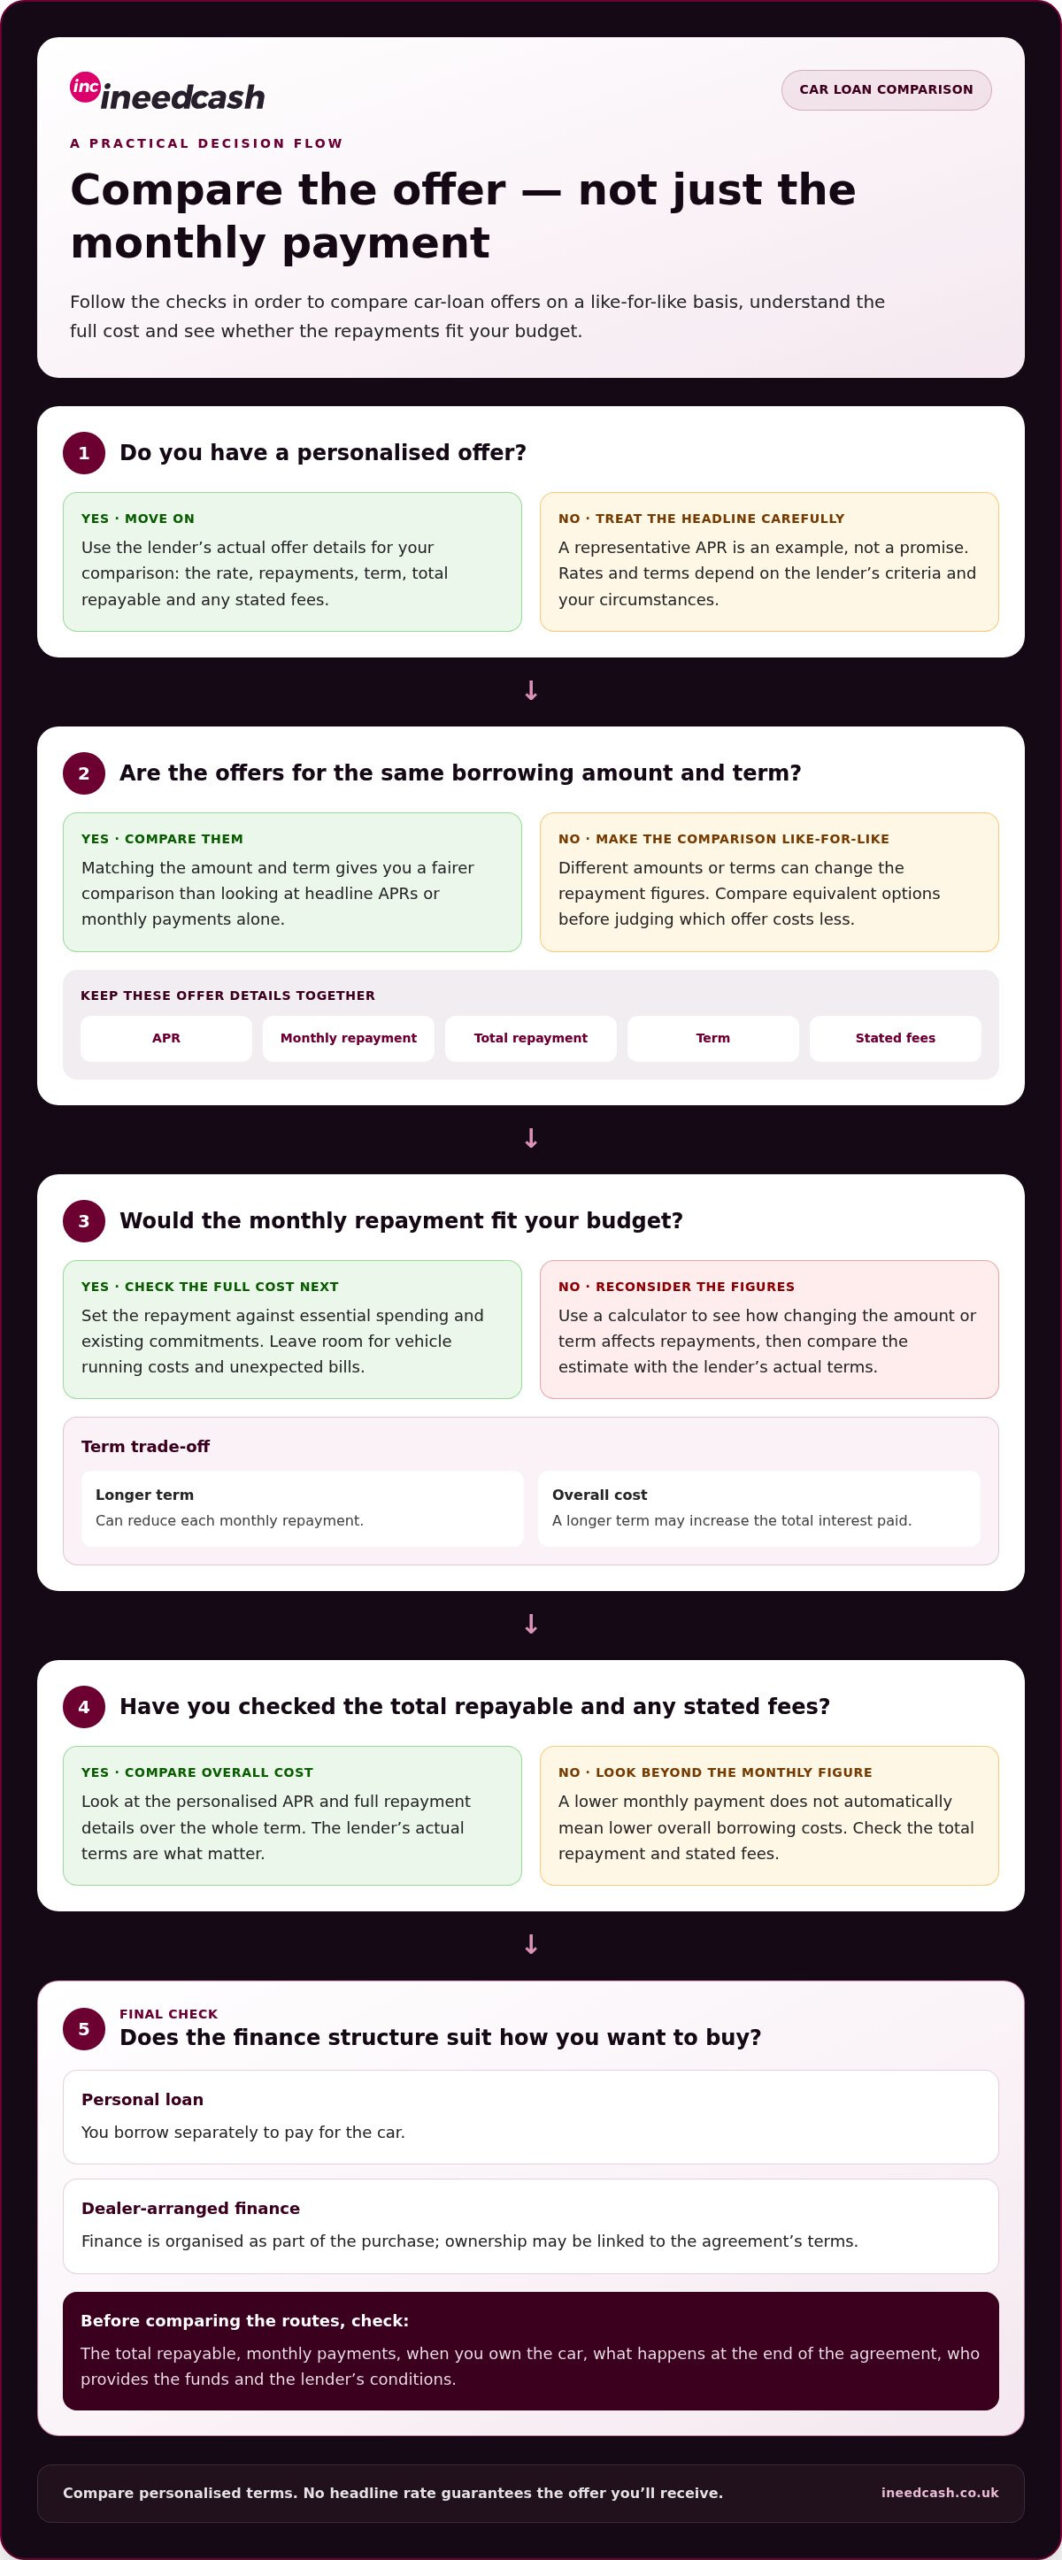
Compare offers for the same borrowing amount and repayment term. This gives you a fairer comparison than looking at headline APRs or monthly payments alone. Record the details side by side:
| What to compare | Offer A | Offer B |
|---|---|---|
| APR | Your offer | Your offer |
| Monthly repayment | Your offer | Your offer |
| Total repayment | Your offer | Your offer |
| Term | Your offer | Your offer |
| Stated fees | Your offer | Your offer |
Look beyond the representative APR
A representative APR is an example rate, not a guarantee of the rate you’ll receive. Once you have a personalised offer, compare its APR and full repayment details, including any stated fees. A lower monthly payment does not automatically mean lower overall borrowing costs. Check the total repayment over the full term to see the difference.
Balance repayments with your budget
A longer term can reduce each monthly repayment but may increase the total interest paid. Use a calculator to see how changing the amount or term affects the figures. Treat the result as an estimate, then compare it with the lender’s actual terms. Before applying, set the proposed repayment against essential spending and existing commitments. Leave room for vehicle running costs and unexpected bills, too.
Car borrowing arrangements can have different structures, so make sure you’re comparing equivalent options. The car finance guide explains how these routes differ. Then compare lenders for car loans by overall cost and whether the repayments look sustainable, not just by the lowest monthly figure.
Ready to explore an option? Start an online quote and review the terms available to you.
Find car-loan lenders through I Need Cash, your UK credit broker
I Need Cash helps you explore vehicle borrowing by connecting applicants with FCA-regulated lenders. Share your details online, then review any quote and the lender’s terms at your own pace. A quote is an option to consider, not a promise of approval or a particular rate. The lender assesses your application and decides whether to make an offer.
What to expect from a broker quote
When you receive a quote, check the borrowing amount, repayment schedule and any conditions before deciding whether to proceed. The FCA’s Consumer Duty guidance says firms should “act to deliver good outcomes for retail customers”. This quotation is from the Financial Conduct Authority’s Consumer Duty guidance. Keep that principle in mind as you consider whether the proposed repayments and terms suit your circumstances.
Prepare before you explore car-loan options
Set a realistic vehicle budget before comparing offers. Consider how much you need to borrow, what repayment you could manage alongside existing commitments and how the vehicle fits your plans. Exploring car finance options can help you understand the borrowing routes before weighing up a specific offer.
When you’re ready, request a free, no-obligation online quote. Take time to review the details and decide whether any option works for you. You stay in control of the next step.
Take your next car-finance step with confidence
Before moving from comparing to signing, check that the written agreement matches the offer you considered. Review the repayment schedule, total amount payable, any stated fees and your responsibilities under the agreement. If anything is unclear, get an explanation before you commit. A careful final read can help you make a considered decision rather than feeling rushed by the excitement of choosing a car.
Keep your priorities at the centre of the decision. The right borrowing option is one that supports your plans without putting unnecessary pressure on your finances. You decide whether to proceed after reviewing the terms, and taking time to think is a sensible part of choosing between lenders for car loans.
I Need Cash is a credit broker, not a lender. Its online quote process starts with a soft search that doesn’t affect your credit score, although a lender may carry out a full check later. Explore your car-loan options with a free, no-obligation quote, then take the time you need to consider what suits you.
Frequently Asked Questions
How long is a car-loan quote valid for?
I Need Cash vehicle quotes are valid for 30 days. Use that time to consider the vehicle you’re planning to buy and check that the quoted borrowing still matches its price. If your plans or the amount you need change, don’t rely on the original figures. Request an updated quote so you can review terms that reflect your current requirements before deciding what to do.
Can a car loan be used to buy a van or motorcycle?
Yes. I Need Cash car-loan options cover new or second-hand cars, vans and motorcycles. Think about how you’ll use the vehicle and how much you need to borrow before exploring a quote. The vehicle and your circumstances may affect the options available, so review the terms provided rather than assuming an offer for one type of vehicle will apply to another.
Do car loans always require a deposit?
No. Many vehicle loans don’t require a deposit, though requirements can differ between lenders and applicants. If you can contribute a deposit, consider how it would change the amount you need to borrow and whether keeping those savings available is more useful. Check the specific offer for its deposit conditions, and make sure a contribution won’t leave you short for essential costs.
Will an initial car-loan quote affect my credit score?
The initial I Need Cash quote uses a soft search and doesn’t affect your credit score. A lender may carry out a full credit check later for certain loan types. Before progressing, read the information provided about any further checks and decide whether you’re comfortable continuing. The initial quote is not a lending decision, so wait for the lender’s terms before making plans around an offer.
Can I repay a car loan early?
Possibly, but the conditions depend on the lender and your agreement. Check the full terms for how early repayment works and whether any conditions or charges apply before making an extra payment or clearing the balance. Don’t assume an early payment will automatically reduce the total cost. If you’re unsure how a payment would be handled, ask the lender to explain the terms of your agreement.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.