 Skip to content
Tesco Car Loan Review: Rates, Eligibility & Alternatives
- Michelle
- Finance
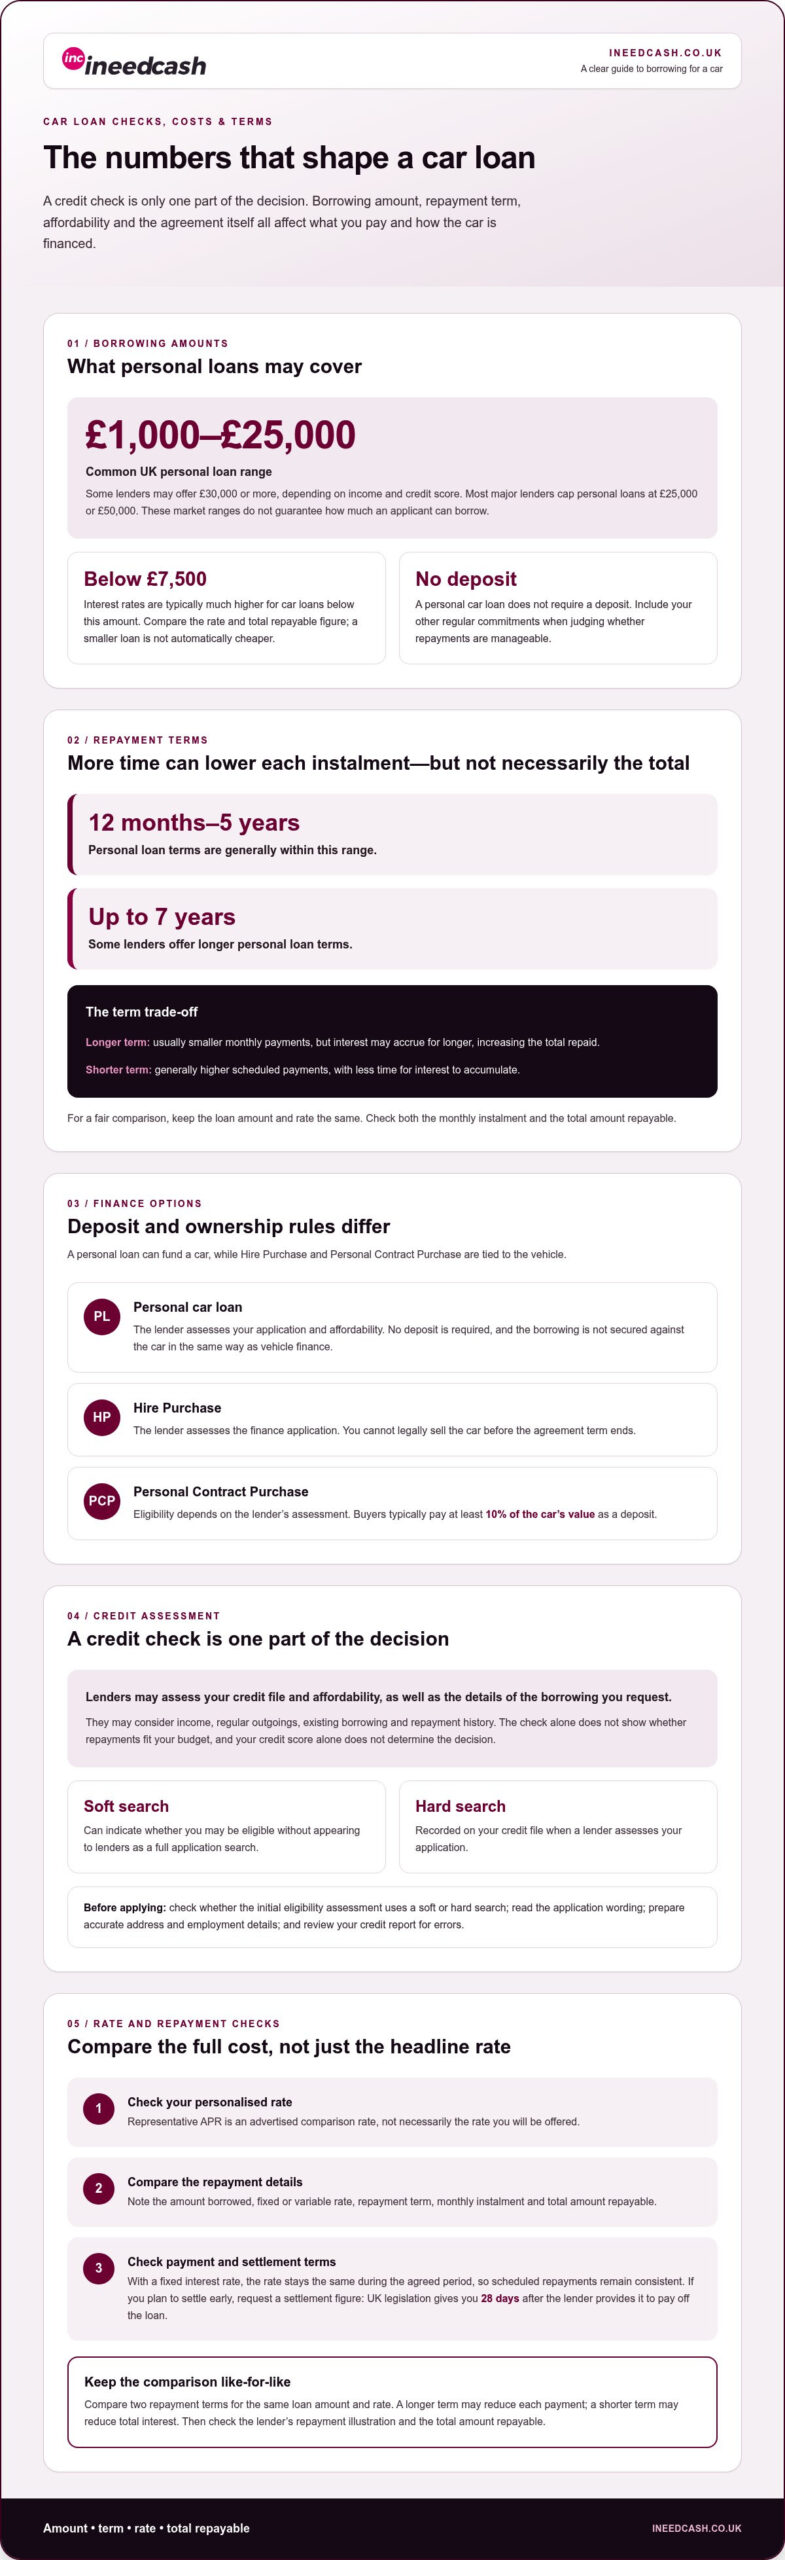
A credit check is part of applying for a Tesco car loan. Lenders also consider affordability and the borrowing details you request, so the check alone won’t tell you whether the repayments suit your budget.
It’s understandable to focus on whether you’ll be accepted, but the total cost and terms matter just as much. This review explains how credit checks fit into a car loan application and compares loan amounts, fixed repayments, repayment terms and representative APR across your options. You’ll also see how personal loans differ from car finance, so you can weigh up the choice that best fits your plans before applying.
Key Takeaways
- Understand why lenders assess your credit and affordability, and what that means when you apply.
- Compare fixed repayments with other car finance arrangements to see how payment structure affects your budget.
- Learn how borrowing amount and repayment term can shape the overall cost, then compare representative APRs carefully.
- Explore whether a homeowner loan could suit your borrowing needs when a standard car finance option isn’t the right fit.
Is a credit check done during my loan application?
Yes. A lender will usually assess your credit file and affordability when you apply for car finance. A Tesco car loan application is assessed against the lender’s criteria and your circumstances, not your credit score alone. A credit check is one part of the assessment, not the whole decision.
Eligibility and credit checks
Before applying, check whether the initial eligibility assessment uses a soft or hard search. A soft search can indicate whether you may be eligible without appearing to lenders as a full application search. A hard search is recorded on your credit file when a lender assesses your application. Read the application wording so you know which type of search will take place.
Lenders also consider income, regular outgoings, existing borrowing and repayment history. The FCA’s consumer credit rules set out requirements for assessing creditworthiness and affordability. Prepare accurate address and employment details, then review your credit report for errors. If a missed payment appears, check that its recorded details are correct before applying.
| Option | Credit and eligibility | Deposit or ownership point |
|---|---|---|
| Personal car loan | Lender assesses the application and affordability | No deposit required |
| Hire Purchase | Lender assesses the finance application | You cannot legally sell the car before the agreement term ends |
| Personal Contract Purchase | Eligibility depends on the lender’s assessment | Buyers typically pay at least 10% of the car’s value as a deposit |
Settlement and choosing an option
Representative APR is an advertised comparison rate, not necessarily your offered rate. Compare your personalised rate and total repayable figure. If you plan to settle a loan early, request a settlement figure. According to UK legislation, you have 28 days after the lender provides that figure to pay it off. Choose the finance option whose eligibility checks, deposit requirements and repayment conditions fit your budget and plans for the car.
Fixed monthly repayments
Fixed repayments make your monthly payments predictable throughout the agreed term. Before choosing, compare the interest rate, payment date and total amount repayable.
Interest rates and monthly repayments
With a fixed interest rate, the rate stays the same during the agreed period, so scheduled repayments remain consistent. A lower annual percentage rate can reduce interest, but compare the representative APR and total amount repayable too. The representative APR is an advertised comparison rate, not necessarily the rate you’ll be offered. Your rate and the amount borrowed both affect your monthly repayments.
Repaying by Direct Debit
If your lender collects repayments by Direct Debit, check the collection date and make sure there are enough funds in the payment account. A missed payment can disrupt your schedule and may have further consequences under the agreement. Set a reminder before the due date and check your balance. Direct Debit is a payment method, not a change to the interest rate or loan term.
Loan terms and monthly payments
The repayment term determines how borrowing is spread across instalments. A longer term usually means smaller monthly payments, but interest may accrue for longer, increasing the total amount repaid. A shorter term generally means higher scheduled payments, with less time for interest to accumulate. Compare terms for the same loan amount and rate, then check that the monthly payment fits your regular budget.
Monthly repayment examples
Use the lender’s personalised offer to build a clear comparison: note the amount borrowed, whether the rate is fixed or variable, the repayment term, monthly instalment and total amount repayable. Compare two terms for the same loan amount. The longer term may reduce each payment, while the shorter term may reduce the total interest. Keep the rate consistent so the comparison shows the effect of the term.
Use the lender’s repayment illustration to check the full cost before committing. If you want to explore borrowing options, get started with an application.
Loan amounts and repayment terms
Does Tesco Bank offer car loans in the UK? A personal loan can fund a car, but it differs from Hire Purchase or Personal Contract Purchase, where the finance is tied to the vehicle. Compare the product type and agreement terms rather than treating all car loans alike.
Borrowing amounts and costs
UK personal loans commonly range from £1,000 to £25,000. Some lenders may offer £30,000 or more, depending on income and credit score. Most major lenders cap personal loans at £25,000 or £50,000. These market ranges aren’t a guarantee of the amount any applicant can borrow.
Interest rates are typically much higher for car loans below £7,500. Compare the rate for the amount you need, alongside the total repayable figure. A smaller loan isn’t automatically cheaper if its rate is higher. For general guidance on comparing borrowing types, read MoneyHelper’s personal loan guidance.
Repayment terms and ownership
Personal loan repayment terms are generally 12 months to five years, although some lenders offer terms of up to seven years. A longer term spreads payments across more months, which can lower each instalment but gives interest longer to accrue. A shorter term can mean higher monthly payments. Compare the total repayable amount as well as the instalment.
Hire Purchase terms are normally 1 to 3 years, while repayment periods are typically 1-5 years. These are distinct market descriptions, so use the specific agreement’s schedule when comparing offers. With a personal loan, the borrowing isn’t secured against the car in the same way as vehicle finance.
Choose an amount that fits
Work out the car’s purchase price, then decide how much you need to borrow. A personal car loan does not require a deposit. Include your other regular commitments when assessing whether repayments are manageable. If you may want to settle early, compare the settlement terms as well as the rate and repayment period.
Representative APR and example repayments
Representative APR can help you compare borrowing costs, but the rate offered to you may differ. Use the lender’s personalised illustration to assess the monthly repayments, loan term and total amount repayable.
Compare the full repayment figures
Compare offers for the same amount borrowed and repayment period. Record each APR, monthly instalment and total amount repayable. This shows whether a lower monthly payment reflects a longer term, a different rate, or both. A Tesco Clubcard reference does not replace the loan illustration: assess the borrowing using its own terms and figures.
The FCA’s Consumer Credit source says: “A firm must undertake an assessment of the creditworthiness of a customer.” This requirement, set out in the FCA Handbook’s CONC 5.2A.4R, is relevant because the rate offered can depend on the lender’s assessment. Treat an advertised representative APR as a comparison point, not a personal quote.
Overpayments and early settlement
Overpayments may reduce the outstanding balance, but the lender’s agreement explains how they affect your repayments or loan term. Check whether an extra payment reduces future instalments or shortens the borrowing period. To repay in full, request a settlement figure and compare it with the remaining scheduled payments, including any charge allowed under the agreement.
Under the Consumer Credit (Early Settlement) Regulations 2004, a lender can charge up to 58 days’ interest when more than one year of the loan term remains. If less than 12 months remain, providers can charge up to 28 days’ interest for full early repayment. Factor the applicable amount into your decision.
Payment breaks and repayment dates
Check the agreement for the first payment date, monthly collection dates and how to request a payment break. A break changes the schedule, so read how it affects later instalments and interest before relying on one. Keep the dates alongside your household budget, and remember that a deferred payment is not a cancelled one.
Compare the lender’s actual terms before choosing. If you want to explore borrowing options, get started with an application.
I Need Cash: Homeowner Loans
If you’re comparing borrowing options beyond car-specific finance, I Need Cash can help you explore Homeowner Loans. As a credit broker, it connects applicants with independent lenders, helping you consider borrowing routes suited to your needs and circumstances.
A Homeowner Loan may be worth exploring if a personal car loan does not suit the amount or repayment structure you’re considering. Compare the proposed repayments, term and total amount repayable carefully. Borrowing against homeownership differs from vehicle finance, so consider whether it fits your wider financial plans, not just the car purchase.
If mainstream borrowing is difficult, I Need Cash also offers Bad Credit Loans and Personal Loans. The right option depends on how much you need to borrow and what repayments you can manage. Visit ineedcash.co.uk to explore your options.
Choose a borrowing route that fits your plans
Before deciding, consider what matters most beyond the car itself: flexibility, protecting your household budget or exploring another borrowing route. A Tesco car loan may be one option to compare, but your choice should fit your wider financial plans as well as the purchase.
Before making a decision, note how much you need, what monthly payment feels manageable and how long you expect to keep the car. Use these priorities to assess each option rather than focusing on one headline figure. If you’re considering alternatives, I Need Cash offers Homeowner Loans, Short Term Loans and Bad Credit Loans. Each is a different borrowing route, so consider which best fits your circumstances and needs.
For a personal conversation about your options, contact I Need Cash about your options. Take your time, stay clear on what you can afford and move forward with confidence.
Frequently Asked Questions
Can I pay my loan back early?
You can usually repay a loan early, but the lender’s agreement sets out the process and any applicable charges. Check whether you’re making an extra instalment or clearing the balance in full, as these may be handled differently. Before sending money, get written confirmation of how the payment will be applied and keep proof of the transaction. This helps you track the remaining balance accurately.
How do car loans work?
A car loan lets you borrow towards a vehicle and repay the lender over an agreed period. Start by setting your budget and working out how much you need, then compare written offers, including repayment dates and total cost. With a personal loan, you use the funds to buy the car. Dealer-arranged finance has its own agreement, so check who owns the vehicle and what happens at the end.
Does Tesco Bank offer car loans in the UK?
A personal loan can fund a car. It differs from Hire Purchase or Personal Contract Purchase, where the finance is tied to the vehicle.
How do you apply for a Tesco Bank loan, and what documents are needed?
Check whether the initial eligibility assessment uses a soft or hard search, then provide accurate address and employment details. Review your credit report for errors before applying.
What happens if you miss a Tesco Bank loan repayment?
A missed Direct Debit can disrupt your repayment schedule and may have further consequences under the agreement. Check the collection date and make sure there are enough funds in the payment account.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.