 Skip to content
Cars and Loans: Your UK Finance Options Explained
- Michelle
- Finance
The lowest monthly payment can still leave you paying more overall. When comparing cars and loans, look beyond what fits your budget each month: the loan term, interest and any final payment all affect the total cost.
A personal loan and dealer finance can work differently, so compare more than the headline rate. This guide covers borrowing for a new or second-hand car, van or motorcycle, and what to check before choosing an option. Compare the total repayable, repayment period, ownership arrangements and lender conditions. I Need Cash is a credit broker, not a lender, and helps applicants explore options from FCA-regulated lenders. An initial quote uses a soft search that doesn’t affect your credit score, although a lender may carry out full checks later. A quote is not a promise of approval or a particular rate.
Key Takeaways
- Cars and loans can involve different borrowing arrangements, so compare how each option affects ownership and payments.
- Look beyond monthly instalments: check mileage terms and what happens at the end of a dealer finance agreement.
- Compare the borrowing amount, budget, APR, total repayable, term and lender conditions.
- I Need Cash is a credit broker working with FCA-regulated lenders, helping you explore vehicle borrowing options. A quote does not guarantee approval.
Cars and loans: what borrowing can help you pay for a vehicle?
A car loan is money borrowed to fund a vehicle purchase and repaid over an agreed term. But “cars and loans” can describe different arrangements, not one standard product. A personal loan and finance arranged through a dealership may have different payment structures, ownership arrangements and end-of-agreement choices. Start by comparing what matters to you: who owns the vehicle, how repayments work, the total repayable and whether each payment fits your budget.
What can vehicle borrowing cover?
I Need Cash Car Loans cover new or second-hand cars, vans and motorcycles. The details of the borrowing arrangement matter, because terms can differ between products. For example, Personal Contract Purchase (PCP) has its own payment structure and end-of-agreement choices. I Need Cash’s car finance options provide a starting point for exploring vehicle borrowing.
Vehicle choice and affordability can shape buying decisions. In September 2026, Geraldine Kilkelly, Director of Research and Chief Economist at the Finance & Leasing Association (FLA), said: “Strong growth in new car finance suggests that consumers remain willing to make significant purchases where confidence and affordability allow. The increasing availability of more affordable new battery electric vehicles is also likely to be influencing buying decisions, encouraging some consumers to choose a new vehicle rather than a used one.”
Budget for more than the monthly repayment
A loan payment is only one part of the cost of owning a vehicle. Before borrowing, factor in other expenses you may need to cover:
- Insurance and vehicle tax
- Servicing, tyres and maintenance
- Fuel or charging
These costs vary with the vehicle and your circumstances. Include them in your monthly budget rather than relying on the repayment figure alone.
Work out what you can comfortably repay after essential bills and vehicle running costs. If the full budget feels tight, reconsider how much you need to borrow or whether taking on repayments now fits your circumstances.
Car loan or dealer finance: how do the options differ?
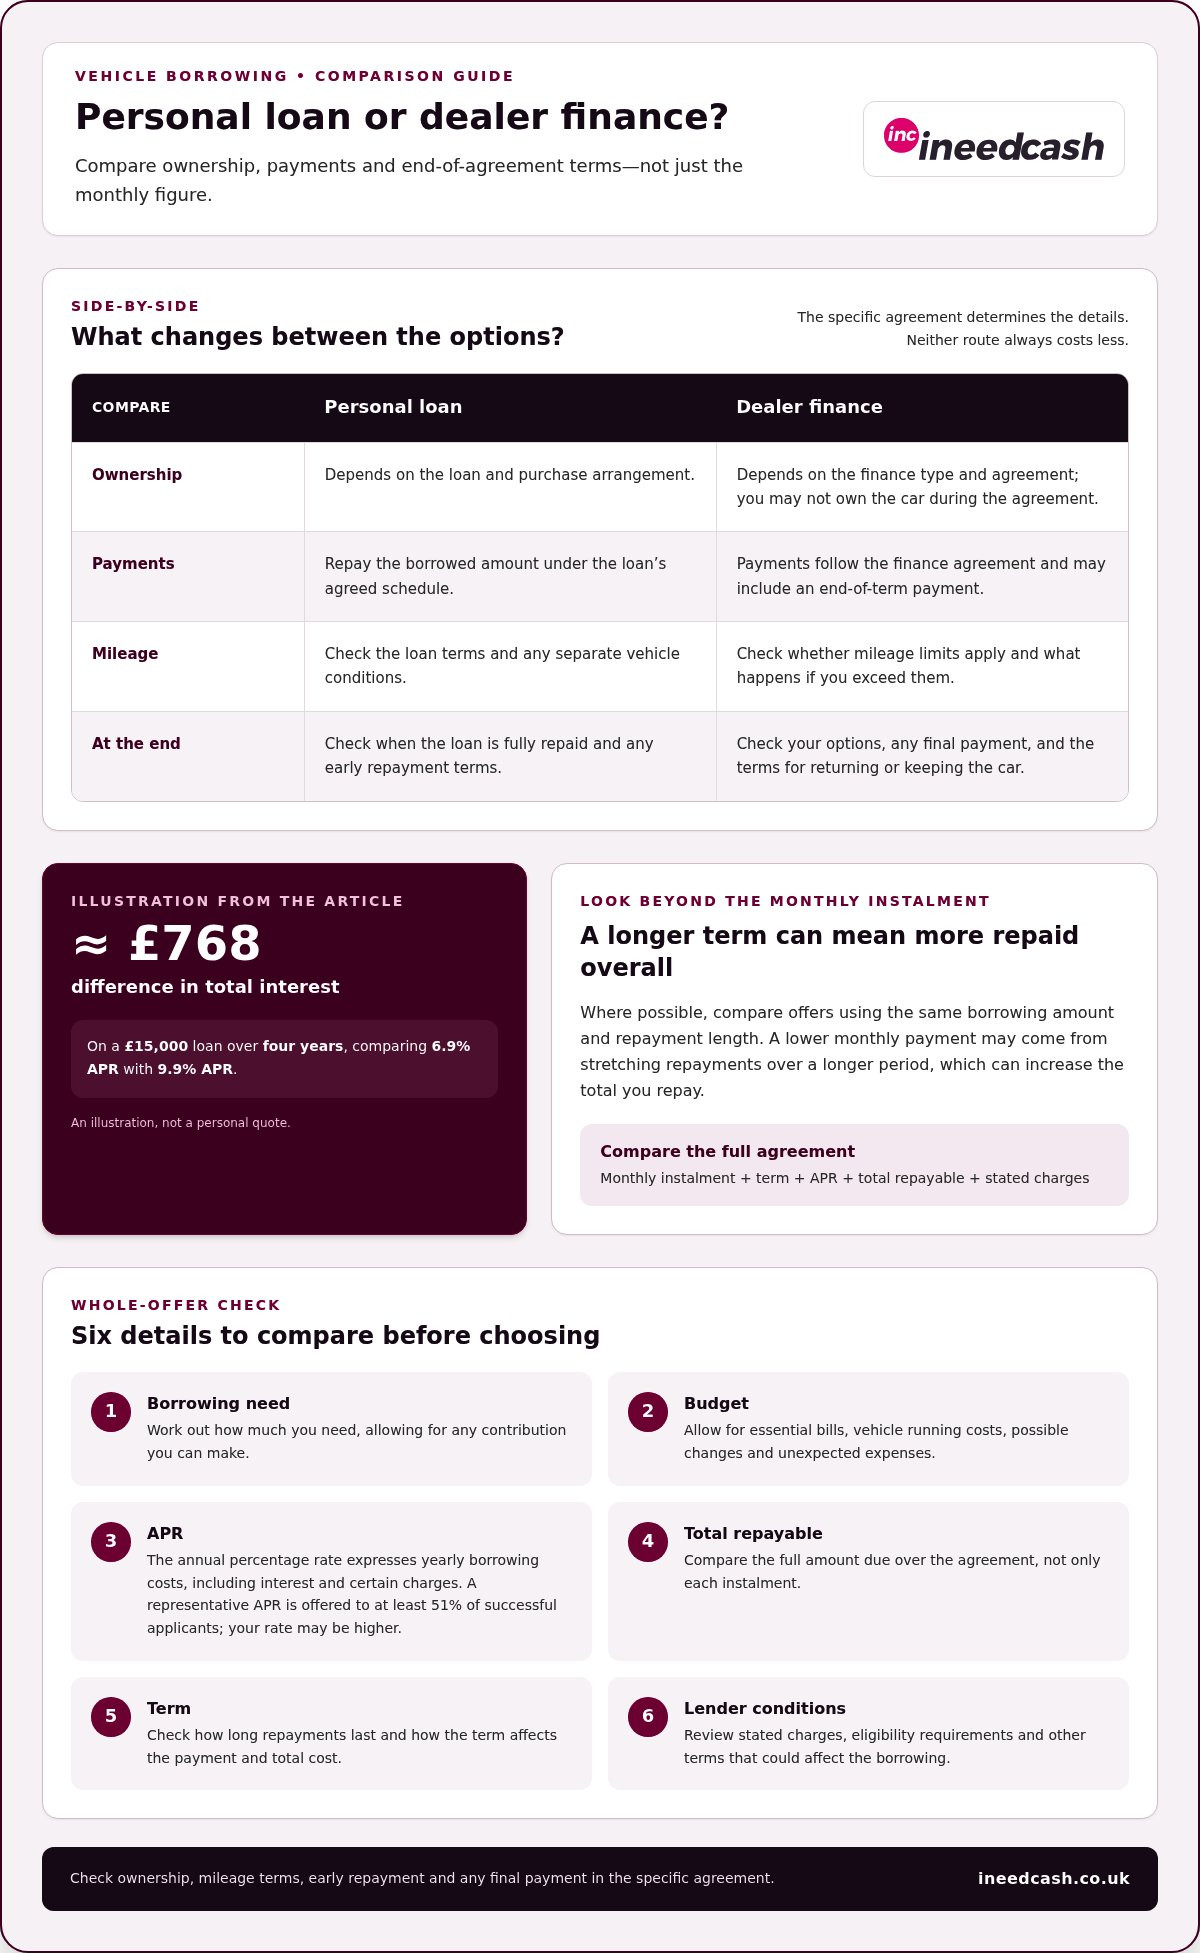
A personal loan is a separate borrowing agreement, while dealer finance is arranged through a vehicle seller and follows the terms of its finance agreement. With cars and loans, compare the agreement rather than just the monthly figure. Ownership, payment structure and end-of-term choices can differ, and neither route always costs less.
| What to compare | Personal loan | Dealer finance |
|---|---|---|
| Ownership | Depends on the loan and purchase arrangement. | Depends on the finance type and agreement; you may not own the car during the agreement. |
| Payments | Repay the borrowed amount under the loan’s agreed schedule. | Payments follow the finance agreement and may include an end-of-term payment. |
| Mileage | Check the loan terms and any separate vehicle conditions. | Check whether mileage limits apply and what happens if you exceed them. |
| At the end | Check when the loan is fully repaid and any early repayment terms. | Check your options, any final payment and the terms for returning or keeping the car. |
When might a personal car loan suit your plans?
A separate loan may suit buyers who want to understand their borrowing and repayments independently from the vehicle purchase. The product name alone does not explain who owns the car or whether restrictions apply. Read the loan terms alongside the sale details, and check how the specific arrangement treats ownership, mileage and early repayment.
What should you understand about dealer finance?
Dealer finance links borrowing to an agreement for the vehicle, so its conditions can differ from those of a personal loan. Before deciding, identify who owns the car during the term, whether mileage limits apply, what choices you have at the end and how early repayment works. Compare the total repayable across the full agreement, not only the monthly instalment.
Once you know which terms matter most, you can explore your borrowing options with a clearer basis for comparison.
How to compare car loans and check affordability
Where possible, compare the same borrowing amount over the same term. A lower monthly payment may come from stretching repayments over a longer period, which can increase the total you repay. The rate matters too: Brumble.co.uk estimates that, on a £15,000 loan over four years, the difference in total interest between 6.9% APR and 9.9% APR is about £768. This is an illustration, not a personal quote. Use the checklist below to assess the whole offer.
- Borrowing need: Work out how much you need to fund the vehicle, accounting for any contribution you can make yourself.
- Budget: Set a repayment you can manage alongside essential bills and vehicle running costs. Allow for possible changes in income or costs, and leave a buffer for unexpected expenses.
- APR: The annual percentage rate expresses the cost of borrowing as a yearly rate, including interest and certain charges. A representative APR is the rate offered to at least 51% of successful applicants. Your rate may be higher, depending on your circumstances.
- Total repayable: Compare the full amount due over the agreement, not only the monthly instalment.
- Term: Check how long repayments last. A longer term can reduce each payment but may mean paying more overall.
- Lender conditions: Review stated charges, eligibility requirements and any other terms that could affect the borrowing.
Which figures should you compare?
Set offers side by side using the same amount and repayment length. Compare APR, total repayable, monthly instalment, term and any stated charges. Actual rates can depend on individual circumstances, so a headline or representative rate is not a guaranteed personal offer. If the terms differ, compare both the total cost and how long you’ll be committed.
What should you check before applying?
Have accurate details of your income, regular spending, employment and address history ready. Check that your budget still works if income falls or costs rise, and avoid relying on every pound of spare income for repayments. An initial soft search is different from a later full credit check. Full checks may follow, so don’t assume every check is soft.
Ready to take an information-gathering step? Explore your car borrowing options.
How I Need Cash can help you explore car loans
I Need Cash is a credit broker, not a lender, and works with FCA-regulated lenders. Its online quote is free and carries no obligation. An initial submission uses a soft search, which doesn’t affect your credit score. A quote does not guarantee approval or a particular rate. Use the information to consider the options presented before deciding whether to continue.
What happens when you request a quote?
Submit an online enquiry with accurate details about your borrowing needs and circumstances. I Need Cash uses this information to explore potential matches from its lender panel. A lender may carry out full credit checks later and makes its own lending decision. You can check a firm’s status using the FCA Firm Checker. If you receive an offer, compare its repayment schedule, total amount payable and conditions with your budget. Requesting a quote is an information-gathering step, not a commitment to accept an offer.
Take a measured next step
Vehicle quotes are valid for 30 days and cover new or second-hand cars, vans and motorcycles. Read the car finance information to understand the borrowing route and consider whether the terms suit your plans. If you have questions about a motor finance agreement, the FCA’s car finance guidance explains its complaints information for consumers.
Take time to weigh any offer against your other commitments, and proceed only if the repayments are affordable. If you’re ready to explore your options, get started with a no-obligation quote.
Choose a next step that fits your plans
A car purchase is a commitment that continues after you collect the keys. Consider how long you expect to keep the vehicle and whether your plans could change. Your borrowing choice should make sense now and fit alongside the priorities you expect to have throughout the repayment period.
Give yourself room to decide. Keep the terms of your preferred option to hand, note any questions and avoid letting an appealing monthly figure rush you into an agreement that doesn’t feel right. The aim of comparing cars and loans is to find a route you understand and can manage, not to borrow simply because an option is available.
To explore options for your circumstances, get started with a no-obligation quote. Review the information provided and decide at your own pace. Compare the total cost and repayment terms before choosing how to move forward.
Frequently Asked Questions
Can I get a car loan for a used car?
I Need Cash Car Loans cover second-hand as well as new cars, plus vans and motorcycles. The lender’s criteria and the terms offered apply. If you’re buying from a private seller or choosing an older vehicle, include the purchase price and vehicle details in your planning, then check that the proposed repayments fit your budget.
Does applying for a car loan affect my credit score?
An initial quote submission through I Need Cash uses a soft search, which doesn’t affect your credit score. This is not the same as every check in the process: a lender may carry out a full credit check if you proceed with a later application. Before taking that step, check what information the lender will assess and whether a full search will be recorded on your credit file.
Is a car loan better than dealer finance?
Neither is automatically the better choice. It depends on your priorities and the agreement. If you expect to drive high annual mileage or keep the car for a long time, mileage rules and end-of-agreement choices may matter as much as the repayment. Compare ownership arrangements and the total commitment for each option, then decide which terms fit your plans and budget.
How long is a car loan quote valid for?
A vehicle quote through I Need Cash is valid for 30 days. Treat it as a snapshot of the options presented, not a guarantee of approval or a promise that a lender will offer identical terms later. Use the validity period to review the details, check whether your circumstances have changed and consider whether the proposed repayments remain manageable before accepting an offer.
Can I get a car loan if I have bad credit?
I Need Cash helps people explore bad credit loan options through its lender panel. Your credit history can affect a lender’s decision and the terms it may offer, and each application is assessed individually. Approval isn’t guaranteed. Consider your current income and commitments first, and proceed only if repayments leave enough room for essential costs.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.