 Skip to content
Lloyds Car Loan: 2026 Rates & Personal Loan Comparison
- Michelle
- Finance
The lowest monthly payment can still lead to the biggest total bill. When weighing up a Lloyds car loan, compare the full amount repayable, whether the repayments fit your budget and what you’ll own at the end.
Lloyds states that existing Lloyds, Halifax and Bank of Scotland current account holders can borrow from £1,000 to £50,000, while new customers can borrow up to £35,000, over one to seven years. These published limits are a starting point, not a personal offer. This guide explains the information Lloyds provides, how a personal loan differs from hire purchase and PCP, and what to check before applying. It also explains how I Need Cash’s online broker service can help you explore car-loan options. I Need Cash is a broker, not a lender. Its initial submission uses a soft search, and its quotes don’t affect your credit score, but a quote or application doesn’t guarantee approval.
Key Takeaways
- Review what Lloyds publishes about borrowing for a new or used car, then check the personalised terms before making a decision.
- Compare a lloyds car loan with PCP and hire purchase by checking ownership, mileage conditions and any final payment.
- Build a realistic budget that includes repayments alongside insurance, fuel or charging, maintenance and vehicle tax where applicable.
- Explore how I Need Cash’s free online broker service connects applicants with vehicle-loan options from FCA-regulated lenders.
Lloyds car loan: what the official information tells you
What can you learn before requesting a personalised Lloyds quote? Lloyds presents borrowing for a new or used car and provides a repayment calculator alongside the option to request a personalised quote. It also publishes representative APRs of 6.2% for hire purchase and 7.4% for PCP on borrowing between £7,000 and £25,000. These figures apply to those finance agreements, not to a personal car loan.
The published personal-loan information doesn’t give one rate that applies to everyone. Use the calculator to estimate repayments, then check the personalised quote and agreement for the terms offered to you. Compare the borrowing amount, term, APR and total repayable, as well as any fees and conditions. Rates and eligibility depend on the offer available to you, so base your decision on the current terms rather than assuming a representative rate will be yours.
What a calculator and personalised quote can, and can’t, tell you
A calculator helps you estimate repayments for a chosen amount and term. Try different terms to see how the monthly payment and total cost change. A longer term can reduce each instalment but may increase the amount you repay overall. A calculator is not a promise of the final cost or confirmation that an application will be accepted.
A personalised quote gives you details based on your circumstances, but read the full agreement before committing. Check the total amount repayable, repayment dates, fees and early-repayment conditions. For a general introduction to borrowing arrangements, Car finance outlines options including personal loans, hire purchase and PCP. Keep comparisons like-for-like: a homeowner loan is a separate borrowing category, so its terms aren’t a direct guide to vehicle finance.
Lloyds car loan versus PCP or hire purchase: understand the difference
A personal loan, hire purchase (HP) and personal contract purchase (PCP) work differently. With a personal loan, you buy the car and own it from the outset, then repay the loan separately. With HP or PCP, the finance agreement sets out who owns the car during the agreement and what choices you have at the end. The comparison below describes these borrowing types, not which agreements Lloyds offers.
Which questions help you compare borrowing routes?
Start with ownership: who owns the car during the agreement, and what do you need to do to own it at the end? MoneyHelper’s UK guidance distinguishes these arrangements by their payment structure and end-of-agreement options. Use the table to identify the questions to ask about an offer, then check the agreement’s specific terms.
| Borrowing type | Ownership and end of agreement |
|---|---|
| Personal loan | You own the car from purchase and repay the loan under its agreed schedule. |
| Hire purchase (HP) | You usually become the owner after making the final payment. |
| Personal contract purchase (PCP) | At the end, you can return the car, pay an optional final balloon payment to own it, or take another agreement, subject to the terms. |
Next, compare the total amount repayable, payment schedule, fees and conditions. A lower monthly payment doesn’t show the full cost or confirm that you’ll own the vehicle. PCP agreements may set mileage limits and return conditions, so consider your expected annual mileage and how you’ll use the car. HP payments go towards the car’s full cost, while a personal loan is separate borrowing used to buy it.
Once you know which arrangement fits your plans, you can explore borrowing options through I Need Cash. It connects applicants with lenders, but the lender decides whether to make an offer.
How to assess a Lloyds car-loan offer against your budget
Set a realistic repayment limit before looking at how much you could borrow. Then check whether that payment leaves enough room for the car’s running costs and changes in your household budget.
What should you check before submitting an application?
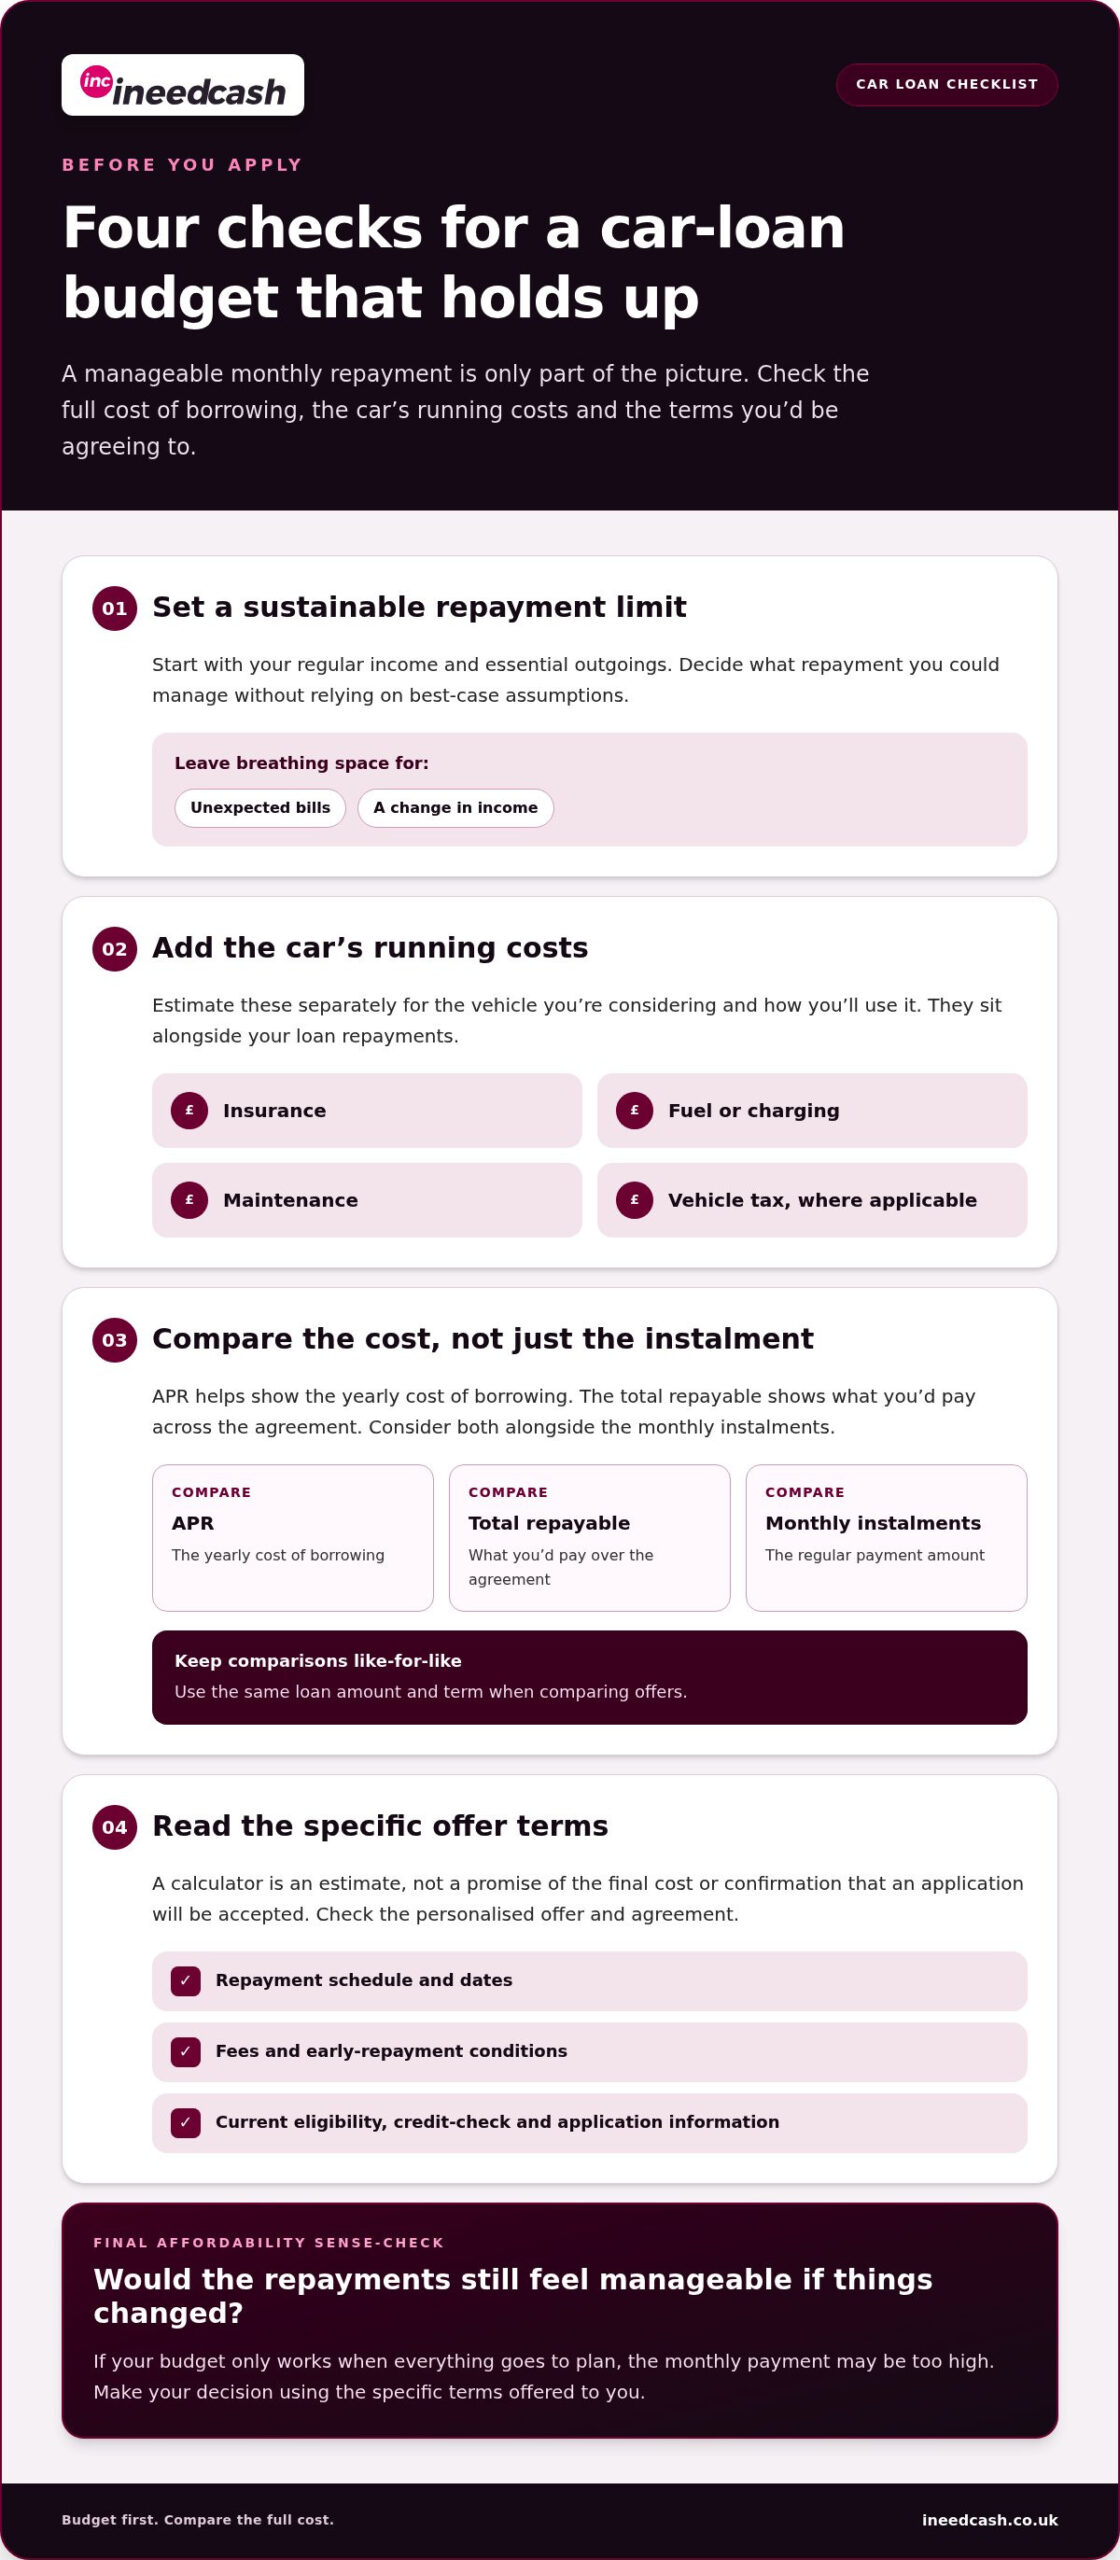
- Set a sustainable budget. Review your regular income and essential outgoings. Decide what repayment you could manage without relying on best-case assumptions, and leave breathing space for unexpected bills or a change in income.
- Include motoring costs. Budget separately for insurance, fuel or charging, maintenance and vehicle tax where applicable. These costs vary by car and how you use it, so estimate them for the vehicle you’re considering.
- Compare the borrowing cost. APR helps show the yearly cost of borrowing, while the total repayable shows what you’d pay across the agreement. Compare both alongside the monthly instalments, using the same loan amount and term for each offer. MoneyHelper’s guide to comparing credit and loans explains how to assess offers.
- Read the specific terms. Check the repayment schedule, fees and early-repayment conditions in the offer. Review Lloyds’ current eligibility, credit-check and application information. General guidance cannot confirm that you’ll be approved or receive a particular rate.
Before committing, consider whether the repayments would remain manageable if your circumstances changed. If your budget only works when everything goes to plan, the monthly payment may be too high.
Pause if an application detail or agreement term is unclear, and get an explanation before proceeding. The FCA’s consumer guidance on credit and loans is another useful resource when weighing up borrowing. Once you’ve set a repayment range, you can explore car-loan options online through I Need Cash. A quote doesn’t guarantee approval.
Considering another car-loan route? How a broker can help
If you’re comparing a Lloyds car loan with other ways to borrow, a broker offers a route beyond applying directly to one bank. I Need Cash is a UK-wide credit broker, not a lender. Its free online service connects applicants with FCA-regulated lenders and covers car loans for new and second-hand cars, vans and motorcycles.
A broker connects you with lenders, but doesn’t make the lending decision. Any offer, rate or approval depends on the lender’s assessment of your circumstances. Treat a quote as an option to review, not a promise that finance will be approved or offered on particular terms.
Explore a vehicle-loan quote without confusing a broker with a lender
The initial submission uses a soft search, and quotes don’t affect your credit score. This gives you a way to explore possible options without mistaking a broker’s matching service for a loan agreement. If a lender makes an offer, read its terms and compare the repayments and total amount repayable with your budget before deciding.
You can use the online service to explore car finance options for your vehicle. The process is separate from Lloyds, and a quote doesn’t guarantee approval. Lenders make their own decisions based on each applicant’s circumstances.
If you’re ready to explore this route, start an online car-loan enquiry. I Need Cash’s Car Loans start from a representative 8.9% APR. The rate and terms offered depend on the lender’s assessment, so compare any offer with your budget and the full repayment before deciding.
Take your next step with confidence
Before applying, set a simple decision rule: decide the monthly amount you can comfortably manage and the vehicle features you need. That gives you a personal benchmark for any offer, including a lloyds car loan, and keeps the decision grounded in your circumstances rather than a tempting headline figure.
Take time to read each offer, note anything you want explained and consider whether the commitment remains manageable alongside your other plans. If the figures or terms don’t feel right, pause and reassess. The right choice is one you understand and can afford, not simply the first option available.
Ready to explore another route? Explore your car-loan options through I Need Cash. The free online broker service connects applicants with FCA-regulated lenders and covers new and second-hand cars, vans and motorcycles. A quote doesn’t guarantee approval, but it gives you an option to consider before deciding whether to proceed.
Frequently Asked Questions
Can I get a Lloyds car loan for a used car?
Yes. Lloyds presents its car loan as an option for buying a new or used car. For a second-hand vehicle, work out how much you need to borrow after accounting for any deposit, then compare the quote with the car’s purchase price. The lender’s decision and final terms depend on your application.
What interest rate does Lloyds charge for a car loan?
There isn’t one rate that applies to every applicant. The rate available to you depends on the personalised terms Lloyds offers. Check its current information and your quote rather than relying on a headline figure or older example. Compare the APR and total amount repayable with other offers using the same borrowing amount and repayment period.
Does applying for a Lloyds car loan affect my credit score?
The effect depends on the type of credit search Lloyds makes at each stage. A calculator or quote is not necessarily the same as submitting a full application. Read the current application information and check whether a search is described as soft or hard before proceeding. Don’t assume that another broker’s or lender’s process applies to Lloyds.
Is a personal car loan better than PCP or hire purchase?
It depends on what matters to you. A personal loan may suit you if you want to own the car from purchase. PCP can offer choices at the end of the agreement, while HP usually leads to ownership after the final payment. Consider how long you expect to keep the car, whether you’re comfortable with any return conditions and whether you can manage a final payment. Then compare the written offers.
Can I compare a Lloyds car loan with options through a broker?
Yes. Compare the same borrowing amount and term, then weigh the APR, total repayable and conditions. I Need Cash is a broker, not a lender, and works with FCA-regulated lenders. Its free online service offers a way to explore car-loan options, but a quote doesn’t guarantee that a lender will approve an application or offer particular terms.
Article by
Mandy Paige
Social Content Writer and Blogger
Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.
Disclaimer
The content of this article/blog was correct to our knowledge on the date/time it was published.