 Skip to content
Cheapest Car Finance Loans: Find the Best UK Rates
- Michelle
- Car Finance, Finance
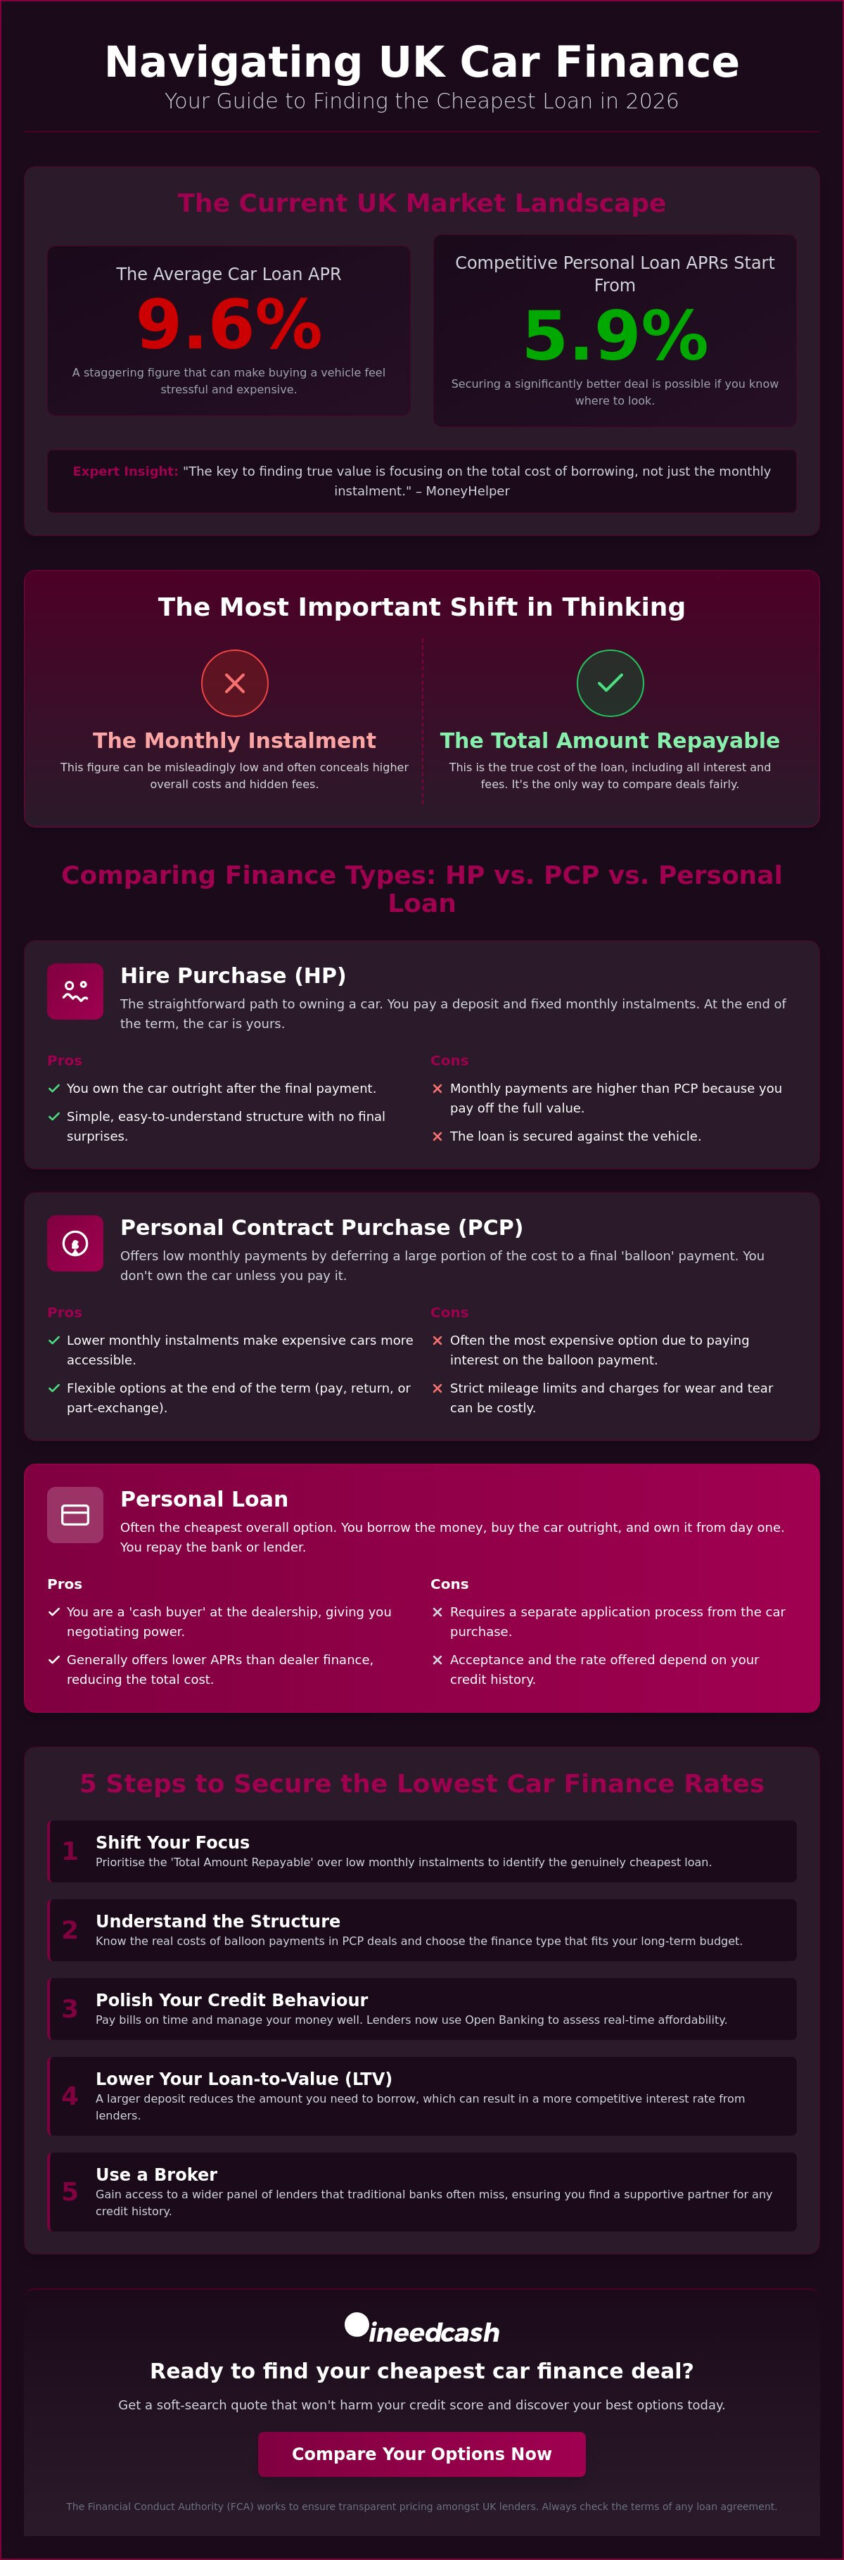
Did you know that the average car loan APR in the UK currently sits at 9.6%? It is a staggering figure that can make any driver feel anxious about their next vehicle purchase. You may feel that finding the cheapest car finance loans is a tough task.
This is true, especially when you compare PCP and HP.
You may also worry about hidden fees. We understand that financial stress; it is why we are here to help you move from anxiety to total empowerment.
You can secure a significantly better deal by understanding the current market landscape. With the Bank of England holding the base rate at 3.75% in June 2026, you can still find strong deals. If you know where to look, there are competitive options.
According to the Financial Conduct Authority (FCA), their motor finance redress scheme is expected to return £7.5 billion to consumers, highlighting just how important it is to have a transparent partner on your side. “The key to finding true value is focusing on the total cost of borrowing, not just the monthly instalment,” notes the advice team at MoneyHelper.
This article helps you navigate the UK market to find the absolute lowest rates and total costs for your next vehicle. We will show you how to get a low-APR loan. We will explain the benefits of a soft search quote. It will not harm your credit score. We will help you avoid hidden traps that catch most buyers out.
Related links How to find cheap, personal car loans Cheapest personal loans UK bad credit: A comprehensive guide to low cost borrowing Understanding the cheapest £1000 loan no credit check How to find the best Car Deals online: A small buyer’s guide Choosing your perfect Car: A smart guide to best loans for cars
Key Takeaways
- Shift your focus from monthly instalments to the Total Amount Repayable. This helps you find the cheapest car finance loans available today.
- Uncover the hidden costs of ‘balloon’ payments and learn which finance type—HP, PCP, or Personal Loan—best suits your long-term budget.
- Master five simple steps to improve your credit behaviour. Lower your loan-to-value ratio for a more competitive interest rate.
- Gain access to a wide panel of lenders that banks often miss. Find a supportive partner, whatever your financial history.
- Understand how the FCA’s transparent pricing protects you from hidden fees. It also helps you get a fair deal on your next vehicle.
What Defines the Cheapest Car Finance Loans in 2026?
Finding the cheapest car finance loans requires looking past the shiny monthly instalment figure. Many buyers choose a deal because the monthly cost seems affordable. Later, they realise they pay thousands more over five years. To secure a true bargain, you must focus on the “Total Amount Repayable”. This figure includes the loan principal, every penny of interest, and any hidden admin fees. Understanding what is car finance? and how its structure affects your long-term wealth is the first step toward financial tranquility. The Financial Conduct Authority (FCA) works hard to ensure clear pricing among UK lenders. This is especially important after the motor finance redress scheme. The scheme is expected to return £7.5 billion to consumers. However, you must still be cautious of the “Representative APR”. This rate only has to be offered to 51% of accepted applicants. If your credit history is less than perfect, you might find yourself in the other 49% who pay more. In 2026, Open Banking is revolutionising this process. Lenders now review your spending in real time, not just your past score. This can lead to more tailored, and sometimes lower, rates if you manage money well.APR vs. Flat Interest Rates: The Hidden Difference
Always prioritise the APR over flat interest rates when comparing deals. A flat rate may look lower because it is based on the original loan amount. APR reflects the reducing balance as you pay it off. APR is the total cost of borrowing including fees and interest. It provides a level playing field for comparing different lenders. Actionable tip: Use a car finance calculator to check the total amount you will repay. This helps you avoid low monthly payments that hide a large overall debt.The Impact of 2026 UK Economic Trends on Borrowing
The Bank of England kept the base rate at 3.75% in June 2026. This has given borrowers a period of relative stability. While the average car loan APR is around 9.6%, lenders now focus on “affordability” in this post-inflation climate. They aren’t just looking at what you earn; they are looking at what you keep. To get the cheapest car finance loans, you must show your spare income can cover repayments without causing financial stress. This supportive approach from lenders aims to prevent buyers from overextending themselves in an uncertain economy.Comparing Finance Types: HP, PCP, or Personal Loan?
Choosing the right structure is vital to securing the cheapest car finance loans. Hire Purchase (HP) is straightforward; you pay a deposit and then monthly instalments until you own the car outright. Because you are paying off the full value from day one, monthly costs are higher. However, you avoid the massive interest charges associated with deferred payments. If you want to own the car long term, this often beats complex dealer deals. There is no “option to purchase” fee. There is no surprise final bill.Why PCP Might Be More Expensive Than It Looks
Personal Contract Purchase (PCP) attracts buyers with low monthly payments. However, it often costs the most in total interest. This happens because of the “balloon payment”—a large sum deferred until the end. You pay interest on this deferred amount throughout the whole term. To protect yourself, always review your consumer rights in car finance. Be wary of mileage limits and damage charges. If you exceed them, a “cheap” deal can quickly become a financial headache. Unsecured personal loans from banks or brokers frequently provide the cheapest car finance loans. Representative APRs for these loans often start from 5.9% for amounts between £7,500 and £25,000. Compare this to the 8.9% or 9.9% common in dealer HP or PCP agreements. By using a personal loan, you become a cash buyer at the dealership. This gives you more leverage to negotiate the car’s price, as the dealer does not need to worry about finance commission.The Homeowner Loan Alternative for High-Value Vehicles
For luxury or high-value vehicles, homeowner loans can offer lower rates. This is because your property is used as security. This often allows for longer repayment terms and larger loan amounts than unsecured options. “Secured debt often has lower interest rates because the lender faces less risk. Still, it is vital to remember your home is at stake,” says Sarah Coles. She is Head of Personal Finance at Hargreaves Lansdown, in a report for the Daily Express. If you want to see what options fit your budget, you can check your eligibility online today.5 Steps to Secure the Lowest Car Finance Rates
Securing the cheapest car finance loans isn’t just about luck. It’s about preparation. You can actively lower your interest rates by following a few simple steps before you even visit a dealership. Start by cleaning up your credit favourite. Check that you are on the electoral roll and dispute any errors immediately. Even small mistakes on your record can place you in a higher interest bracket. This can cost you hundreds of pounds over the loan’s life.Boosting Your Credit Score for a Better Tier
Lenders in 2026 use highly sensitive scoring models from agencies like Equifax and Experian. These models prioritise stability and recent behaviour. To help you qualify for the best tiers, avoid any new credit applications for three to six months. Do this before you apply for your car loan. This “quiet period” shows lenders you are not desperate for cash. It makes you a more attractive, lower-risk borrower. When comparing finance types, remember that your score dictates the APR you’ll actually receive. Next, focus on your deposit. Increasing your down payment reduces the Loan-to-Value (LTV) ratio, which often triggers a lower interest rate. Aim for at least 10% to 20% of the car’s value. You should also opt for the shortest repayment term you can comfortably manage. Whilst a longer term lowers monthly costs, it massively increases the total interest paid.The ‘Sweet Spot’ for Loan Duration
A 36-month term is often the most cost-effective balance. Data shows that stretching a loan to a 60-month term can nearly double the total interest paid compared to a 36-month term. This is a common trap that makes “cheap” monthly payments very expensive in reality. Finally, use a broker to perform a soft search. This allows you to see quotes from a panel of lenders without impacting your credit file. Avoid dealer add-ons like GAP insurance or paint protection; these are almost always cheaper when bought independently. If you want to find the cheapest car finance loans for your situation, get started with a quote today.How a Broker Finds the Cheapest Deals for All Credit Types
Direct banks are gatekeepers. They have one set of rules. If you do not fit their narrow criteria, you may get a high-interest offer. Or they may reject you outright. A broker acts as your advocate instead. By accessing a wide panel of lenders, a broker finds the cheapest car finance loans for your financial behaviour. This is vital in the current economic climate. The Office for National Statistics (ONS) reports that budget pressures are changing how we borrow. “The broker model boosts competition. It helps people with thin credit files. They can still get the cheapest car finance loans through specialist panels. This is noted in a summary from the Competition and Markets Authority.Soft Searches: Comparing Rates Without the Risk
Fear of rejection often stops people from shopping around. Traditional “hard” credit checks leave a mark on your file, which can temporarily lower your score. Soft search technology changes the game. It allows you to see multiple real-world quotes without any impact on your financial records. This transparency is a core part of finding a low-APR deal whilst protecting your future borrowing power. It moves you from a state of uncertainty to one of total control.Specialist Lenders for Unique Situations
Bad credit isn’t a barrier to a competitive deal in 2026. Lenders now use Open Banking to look at your current money management rather than just mistakes from years ago. If you are self-employed or need bad credit car finance, specialist lenders on a broker’s panel may offer better rates. High-street banks often cannot match them. Be honest about your outgoings during the application. This helps you secure the cheapest deal. It also makes sure it suits your lifestyle. At I Need Cash, we believe in personal autonomy and individualized conditions. We streamline the entire process, connecting you to our extensive network of providers in minutes. You get the speed of a digital-first intermediary backed by a supportive, non-judgmental approach. We work on your behalf to find a solution that fits your budget perfectly. Secure your quote today and experience a risk-free journey toward your next vehicle purchase. For those purchasing a vehicle to support a new business venture or delivery service, you can also explore Same Day Courier solutions to help get your logistics operations off the ground immediately.Drive Away with Confidence and Real Savings
You now have the tools to secure the cheapest car finance loans without the stress of traditional banking hurdles. By focusing on the total amount repayable rather than just monthly costs, you protect your long-term wealth. Remember that your recent financial behaviour and a healthy deposit are your best assets for unlocking lower interest rates. Whether you choose HP to own the car, or an unsecured personal loan for flexibility, your route to a better deal is clear. As an FCA Authorised and Regulated facilitator, we provide a safe and ethical way to explore your options. Our quick and easy online application gives you access to many UK lenders, so you can find support. You will find a partner that respects your independence. Take the final step toward your next vehicle with total tranquility. We are here to help you move from financial anxiety to empowerment. Get a personalised car finance quote today with no impact on your credit score. You deserve a deal that works for your specific needs, and we are ready to assist you in finding it.Frequently Asked Questions
What is a good APR for car finance in 2026?
A good APR in 2026 typically starts from 5.7% for loans over £25,000 or around 5.9% for amounts between £7,500 and £15,000. With the Bank of England base rate at 3.75%, any offer below the national average of 9.6% is competitive. Your specific rate will depend on your credit behaviour and the total amount you intend to borrow. Smaller loans under £5,000 usually carry higher rates, often starting from 9.2% APR.Can I get the cheapest car finance with a bad credit score?
You can still get the cheapest car finance loans for your credit tier, even if your financial history is not perfect. Modern lenders use Open Banking to assess your current affordability and spending patterns. They do not just look at old defaults. By working with a broker like I Need Cash, with access to specialist panels, you can find lenders. These lenders value your current stability. This approach ensures you get the most competitive rate available for your unique circumstances.Is it cheaper to get a personal loan or dealer finance?
It is generally cheaper to use an unsecured personal loan from a bank or broker than to choose dealer-led finance. Representative APRs for personal loans often start at 5.9% for mid-range amounts. Dealer HP or PCP deals often begin at about 8.9% or higher. Using a personal loan also turns you into a cash buyer at the dealership. This gives you significantly more leverage to negotiate a lower price on the vehicle itself.How does a larger deposit affect my car loan interest rate?
A larger deposit lowers your Loan-to-Value (LTV) ratio. This often moves you into a lower interest rate bracket. Lenders view a significant down payment as a sign of financial stability and reduced risk. Aiming for a deposit of 20% can help you secure the cheapest car finance loans by proving your commitment. This not only reduces your monthly instalments but also slashes the total interest you pay over the entire term.What happens if I want to pay off my car loan early?
You have a legal right to pay off your car loan early under the Consumer Credit Act. Most lenders will apply an early settlement fee, which is typically equivalent to one or two months’ interest. Even with this fee, clearing the balance early usually saves you a significant amount in future interest charges. Always ask your lender for an official “settlement figure”. This shows how much you could save by ending the agreement early.Related links How to find cheap, personal car loans Cheapest personal loans UK bad credit: A comprehensive guide to low cost borrowing Understanding the cheapest £1000 loan no credit check How to find the best Car Deals online: A small buyer’s guide Choosing your perfect Car: A smart guide to best loans for cars
Article by
Mandy Paige
Social Content Writer and Blogger Mandy has been writing for various website for a number of years, especially for companies in the consumer finance industry. She started her career guiding customers wanting help when applying for finance at a Loan Brokerage. Speaking to individuals wanting guidance, it lead her to start writing help and guidance on finding the right solution for their needs. Outside of writing, she is a wiz with a pair of scissors as she originally trained as a hairdresser.